If You Invested $1000 In Microsoft 30 Years Ago

So, picture this. It’s 1994. You’re at a friend’s house, and they’re showing off this weird new thing called the “World Wide Web” on a bulky beige computer. You have zero idea...

So, picture this. It’s 1994. You’re at a friend’s house, and they’re showing off this weird new thing called the “World Wide Web” on a bulky beige computer. You have zero idea what it is, but you’ve got a spare grand burning a hole in your pocket. Instead of buying that new Nirvana CD, you take a flyer on a software company called Microsoft. What if you actually did?
Let’s rewind the tape. Thirty years ago, Bill Gates was already a big deal, but Microsoft was still a scrappy underdog. Windows 95 hadn’t even launched yet. You’d be buying in at a time when most people thought “PC” meant “Politically Correct.” Your $1,000 back then would have snagged you about 95 shares, adjusted for splits. Sounds modest, right?
But here’s where the magic—or madness—kicks in. Microsoft has split its stock nine times since 1987. By 1994, you were already sitting on shares from earlier splits. Today, those 95 shares would have multiplied into over 28,000 shares. Yeah, let that sink in. You’d be holding a mountain of stock.
Must Read
The Stock Price Rollercoaster
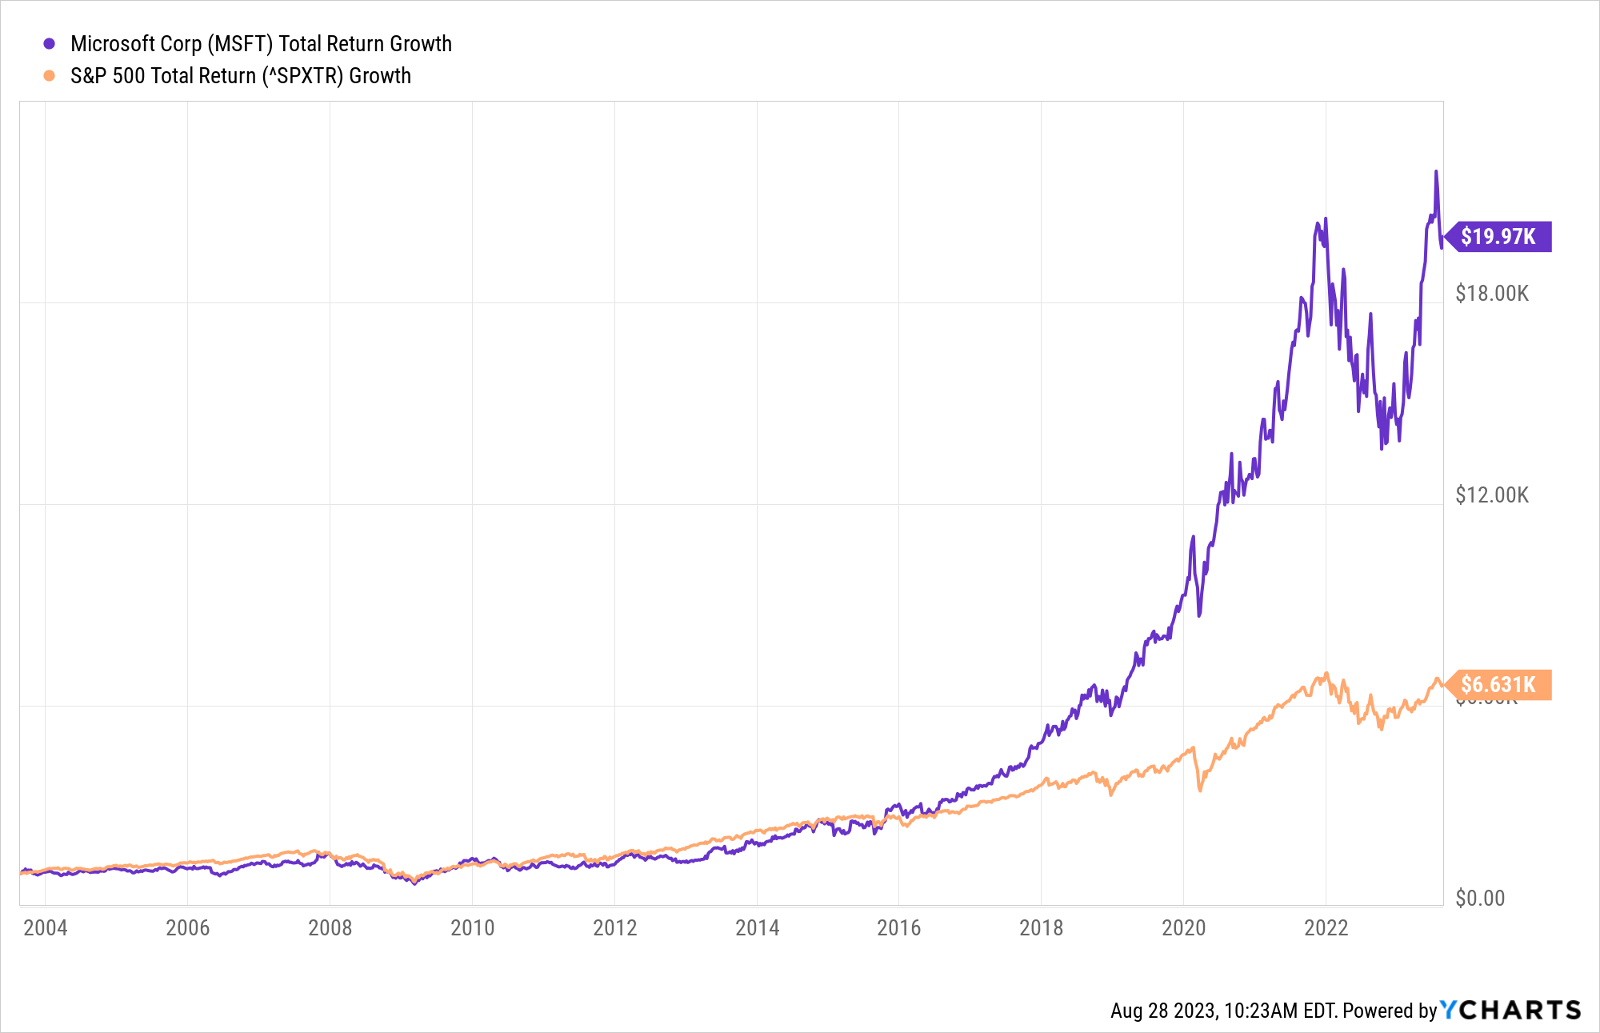
In 1994, Microsoft was trading around $5 per share (adjusted for splits). Today, it’s hovering near $400. That’s a 7,900% increase in price alone. But hold up—that’s just the raw share price. You also got dividends, which Microsoft started paying in 2003. Those checks add up.
Pretend you reinvested every dividend. You’d have waaay more than 28,000 shares now. We’re talking over 40,000 shares. At today’s prices, that’s a cool $16 million. Sixteen million dollars from a single grand. That’s not a misprint.
Let’s get real: you probably would have sold somewhere along the way. Maybe in 2000, when the dot-com bubble burst and the stock tanked. Or in 2008, when the financial crisis hit. Hindsight is a ruthless comedian. But if you held on, you’d be richer than most people’s wildest dreams.
What This Tells Us About Investing
This isn’t a story about luck alone. It’s about patience and time in the market, not timing the market. Microsoft had epic drops—like losing 45% in 2000. But it also had rebound after rebound. The key? They dominated PCs, then the cloud, and now AI.
 If You Invested $1,000 in Microsoft When It First Declared a Dividend
You might be thinking: “I don’t have a time machine.” True. But the lesson is that compounding works if you let it. A boring S&P 500 index fund over 30 years would have turned $1,000 into roughly $8,000—still decent. Microsoft was just the rocket fuel version.
Side note: Nobody bought Microsoft in 1994 thinking it would be worth $3 trillion. They bought it because it was a good business. That’s the irony. You don’t need to predict the future; you just need to bet on durable companies.
The Downside (Because It’s Not All Kumbaya)
Let’s be real for a second. If you had invested $1,000 in Enron back then, you’d have zero bucks today. Microsoft was a huge risk in 1994—the internet was unproven, and competitors like Lotus and WordPerfect were breathing down their necks. You could have just as easily lost your shirt.
Also, imagine sitting through the 2000 crash. Your $1,000 would have peaked at nearly $7,000, then plummeted to $2,500. Holding on through that emotional rollercoaster? Tough. Most people sold in panic. You’d need nerves of steel.
 If You Invested $1000 In Microsoft 30 Years Ago | Detroit Chinatown
And don’t forget inflation. $1,000 in 1994 is worth about $2,100 today. So your “real” return is still astronomical, but it’s good to keep perspective. Oh, and taxes? You’d owe capital gains unless you were clever with an IRA. Our government always wants a slice.
What Would You Do Today?
If you’re reading this, you’re probably wondering: “Should I buy Microsoft now?” Don’t chase past returns. Microsoft is a great company, but it’s trading at 35 times earnings. That’s pricey. The growth might be slower than the last three decades.
Instead, think about today’s “Microsoft.” Could it be a company like Nvidia, Amazon, or even a small biotech firm? Nobody knows. But the strategy stays the same: buy good businesses, hold for decades, and ignore the noise.
One more thing: You don’t need $1,000. Even $100 a month in an index fund can grow into a life-changing sum. Start small. Let time do the heavy lifting. The next 30 years will pass anyway—why not make them work for you?
So, back to that $1,000. If you actually invested it in Microsoft in 1994, you’d probably be sipping margaritas on a yacht right now. But since you didn’t, don’t beat yourself up. We’re all in the same boat. The real gift is the lesson: compound interest is the eighth wonder of the world. Or, as Albert Einstein allegedly said, “He who understands it, earns it; he who doesn’t, pays it.” Go earn it.
