Does Insurance Cover Hrt For Perimenopause
Let’s be honest, perimenopause shows up like an uninvited guest who rearranges your furniture at 2 AM. One minute you’re fine, the next you’re crying at a car commercial while...
Let’s be honest, perimenopause shows up like an uninvited guest who rearranges your furniture at 2 AM. One minute you’re fine, the next you’re crying at a car commercial while simultaneously having a hot flash so intense you could fry an egg on your forehead. It’s a wild ride, and many of us are looking for a little backup—namely, Hormone Replacement Therapy (HRT).
But then comes the big, buzzkill question that sits in the back of your mind like a mosquito you can’t swat: Does my insurance cover this? It’s a fair query. You’re already dealing with brain fog and mood swings; the last thing you need is a surprise bill that looks like a car payment.
The Short, Sweet Answer
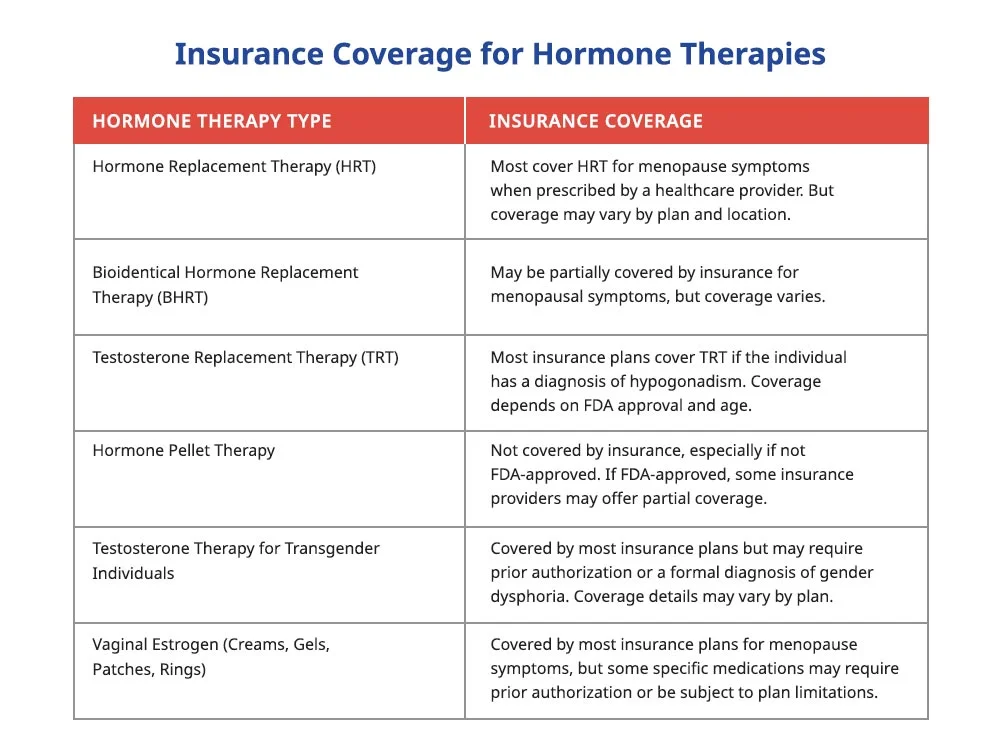
Here’s the good news you can almost feel in your bones: Yes, most insurance plans do cover HRT for perimenopause. Think of it like this—your insurance company has grudgingly agreed that treating a medical condition (which perimenopause absolutely is) is cheaper than ignoring it.
Must Read
But—and you knew a “but” was coming, right?—the coverage is not always a smooth, easy glide. It’s more like trying to parallel park a minivan on a busy street. You’ll get there, but you might need to make a few adjustments.
The “Why” Behind the Coverage
Insurance companies love numbers, even if we don’t. They have realized that managing symptoms like crushing fatigue, bone density loss, and that weird anxiety that pops up for no reason is way cheaper in the long run than treating broken hips or heart disease later. So, you paying for a patch or a cream is actually a bargain for them.
Imagine your body is a slightly rusty, classic car that needs a tune-up. HRT is the good oil and the spark plugs. Your insurance plan doesn’t want you to blow a gasket on the highway of life. They want you to keep chugging along, and they’ll usually pay for the standard maintenance, at least for a while.
The Fine Print That Makes You Squint
Now, here is where the story gets a little twisty. Not every plan throws a party for every type of HRT. Just like you have to choose between a latte and a cappuccino, you might have to choose between bioidentical hormones and synthetic ones.
Your insurance might love a generic pill that’s been around since your grandma’s day, but balk at a fancy compounded cream from a special pharmacy. It’s like they’re saying, “You can have this reliable sedan, but we aren’t paying for the convertible with heated seats.”
The “Prior Authorization” Dance
This is the part of the process that feels like a weird little office choreography. Your doctor writes a prescription, but insurance says, “Hold your horses, we need to know why you really need this.” It’s called a prior authorization (PA).
Don’t panic. It’s not a rejection; it’s just insurance being nosy. Think of it as your doctor writing a very polite note that says, “Dear Insurance, Sarah here really needs this cream because she nearly threw a stapler at the office coffee machine last week. Please help.” Usually, it gets approved.
 How Much Does Hormone Replacement Therapy Cost? | Activ8 Health
What About Those “Do-It-Yourself” Fixes?
You might see ads for fancy herbal supplements or “hormone balancing” kits online. Let me save you some cash here: your insurance almost never covers those. They consider them like you buying a fancy scented candle—nice, but not medically necessary.
Stick with the stuff your doctor writes on an official prescription pad. That’s the golden ticket. The patches, the gels, the pills that come from a regular pharmacy? Those are your insurance company’s jam.
How to Be Your Own Hero (Without the Cape)
First, log into your insurance account. I know, it’s boring, but it’s easier than a surprise bill. Search for something like “drug formulary” or “menopause coverage.” It’s a list of what they’ll pay for, and it’s usually written in a language that’s 60% English and 40% bureaucratic gobbledygook.
Second, talk to your doctor like they are a friend who speaks “insurance.” Ask them directly: “Will my insurance fight me on this? Which version is easiest to get covered?” They’ve done this dance a thousand times.
The Little Victory Dance
I have a friend, let’s call her Jen, who was sweating through every single meeting at work. She finally called her insurance, armed with a term she heard on a podcast: “menopausal hormone therapy is preventative.” The customer service rep paused, and then said, “Oh, yes, that’s covered at 80%.” Jen almost cried happy tears into her keyboard.
That phone call took ten minutes. Ten minutes to save hundreds of dollars and get her sleep back. It’s worth the mild awkwardness of asking, “Does my plan cover the Estradiol patch, specifically?”
So, What’s the Verdict?
Don’t let fear of a bill stop you from asking for help. The system is built to be confusing, but it is also built to mostly cover this. Consider perimenopause the unplanned home renovation of your forties and fifties. The contractors (your doctors) are ready, and the bank (your insurance) usually writes the check.
So take a deep breath. Make that phone call. You’ve navigated worse things—like assembling flat-pack furniture or dealing with a teenager’s mood. This? You’ve got it. And your future, less-sweaty self will be very grateful you asked.
