How To Endorse A Business Check To Someone Else
Picture this: you’re holding a business check made out to your company, but the funds are actually meant for a freelancer, a partner, or a vendor down the street. It’s a class...

Picture this: you’re holding a business check made out to your company, but the funds are actually meant for a freelancer, a partner, or a vendor down the street. It’s a classic modern hustle—money flows through you, not to you. Endorsing that check over to someone else isn’t just legal; it’s a vibe if you know the steps.
Before we dive into the ink, let’s get one thing straight: this is not a casual favor. Business checks carry more weight than your personal paycheck—they’re legal documents with tax implications. The IRS tracks these moves, so treat the process like you’re curating a playlist: deliberate, accurate, and a little cool.
The Endorsement Dance
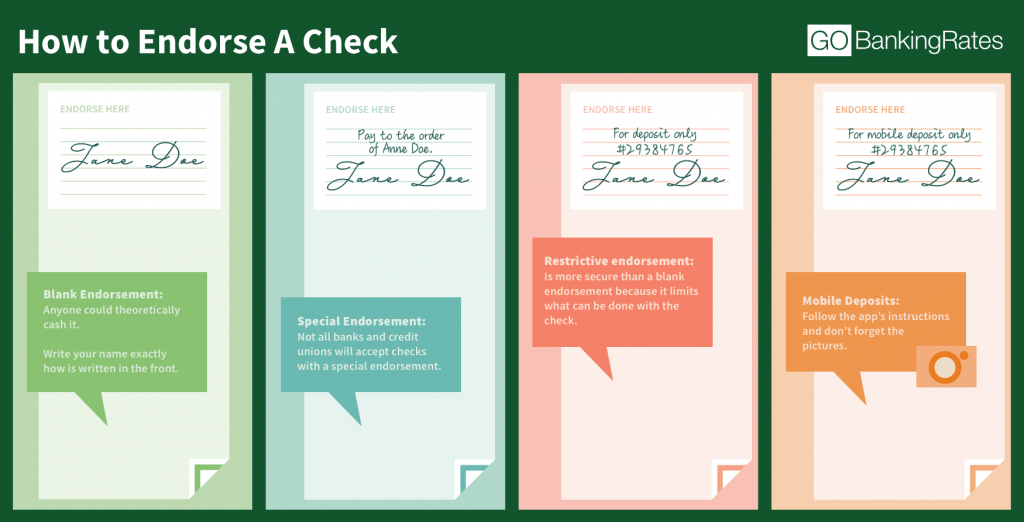
To start, flip the check over and look at the back. You’ll see a box or line labeled “Endorse Here”—that’s your stage. Never sign below that line; that zone is for the bank’s stamps, and crossing it is like wearing socks with sandals: technically allowed, but deeply awkward.
Must Read
Write: “Pay to the order of [Full Name of Person or Business]” directly in the endorsement area. Then, sign your name exactly as it appears on the front of the check—no middle initials unless they’re printed there. If your business name is “Cool Beans LLC,” don’t get cute with “Cool Beans Inc.”
Pro tip: Use a fine-tip black or blue pen. Gel pens are fine, but avoid glitter or metallic ink—bank scanners hate a party. Fun fact: The word “endorse” comes from the Latin indorsare, meaning “to put on the back.” You’re literally continuing a 500-year-old tradition.
When the Bank Says “Nah”
Not all business checks are created equal. Some banks require a restrictive endorsement—you add “For Deposit Only” above your signature to limit where the money lands. This is your security blanket; it prevents random people from cashing it at a pawn shop (yes, that happens).
If the check is for more than a few thousand dollars, call your bank ahead. They might demand a medallion guarantee—a fancy stamp that confirms your signature is legit. Think of it as the velvet rope for VIP transactions.
Cultural side note: In the movie Ocean’s 11, they forged signatures to cash stolen checks. You’re doing the opposite—you’re being transparent. You get the glamour of a heist movie without the prison time.
Paperwork: The Unsexy Hero
After the check is signed, you’ll need a business resolution if you’re a corporation or LLC. This is a document from your board or owners that says, “Yes, Alice can sign checks on our behalf.” Without it, banks may freeze the funds like a cryogenic egg.
 How To Endorse Business Checks? – HXDM
If you’re a sole proprietor, you’re the captain and the crew—just keep a receipt or invoice confirming the transfer. The IRS loves paper trails more than your mother-in-law loves unsolicited advice. Save everything for tax season.
Fun fact: The oldest surviving check dates to 282 BCE in ancient Greece. It was basically a clay tablet saying, “Pay this farmer.” Your paper check is part of a 2,300-year-old lineage—treat it with respect, not like a napkin.
The Digital Twist
If you use mobile deposit, you can still endorse a check to someone else—but it’s trickier. Never take a photo of an already-endorsed check; that can cause duplicate deposits and bank meltdowns. Instead, write “For Mobile Deposit Only” and skip the “Pay to the order of” part temporarily.
Hand the physical check to the recipient, and have them endorse it on the back at their bank. This avoids the digital version of a stolen identity. It’s like passing the remote control—smooth, clear, and no arguments.
If you’re feeling extra modern, use a service like Venmo or Zelle for the transfer after you cash the check yourself. This bypasses the awkward endorsement entirely, though you’ll owe self-employment tax on the income. Convenience has a price, like avocado toast.
Pitfalls That’ll Make You Cringe
Mistaking the spelling of the recipient’s name can trigger a “returned check” fee—typically $20 to $50. Double-check the spelling like you’re typing a crush’s name in a text. Example: If they go by “Jonathan,” don’t write “John.”
 How to Endorse a Check & Where to Sign (Steps) | GOBankingRates
Also, never endorse a check in front of the person you’re giving it to. This opens the door to fraud—they could see your signature and copy it. Endorse in private, like a spy passing a microfilm.
One time, a friend endorsed a business check at a coffee shop and left it on the counter. The barista found it, cashed it, and bought 400 lattes. Don’t be that friend. Your signature is your digital fingerprint in ink.
The Grand Gesture
Handing over an endorsed business check is a form of trust—like giving someone your house keys. It says, “I value your work enough to be part of your financial flow.” So, do it with a short, polite handoff: “Here’s the check for the project. Thanks for crushing it.”
If you’re the recipient, say “Thank you” and don’t ask for the pin code to their bank account. Manners matter more than money—especially in business, where reputation moves faster than any check.
Final tip: Snap a photo of the endorsed check before handing it over. You’ll need it for your records, and it’s a subtle flex that says, “I’m organized.” Your future self will thank you when tax season calls.
Reflection: Endorsing a check to someone else isn’t just a transaction—it’s a mirror of daily life. We’re always passing things along: a favor, a lead, a smile at the grocery line. The skill is in doing it with clarity and care, so no one gets lost in the exchange. Next time you sign that back, remember: you’re not just moving money—you’re moving trust. And that’s the hardest check to fake.
