Compare Types Of Retirement Accounts Answer Key

So, you’ve finally decided to peek into the mystical world of retirement accounts. It’s less like a treasure map and more like a bureaucratic maze designed by a caffeinated sq...

So, you’ve finally decided to peek into the mystical world of retirement accounts. It’s less like a treasure map and more like a bureaucratic maze designed by a caffeinated squirrel. But stick with me—I’m about to hand you the answer key to this confusing exam called “Your Financial Future.”
The Big Kahuna: The 401(k)
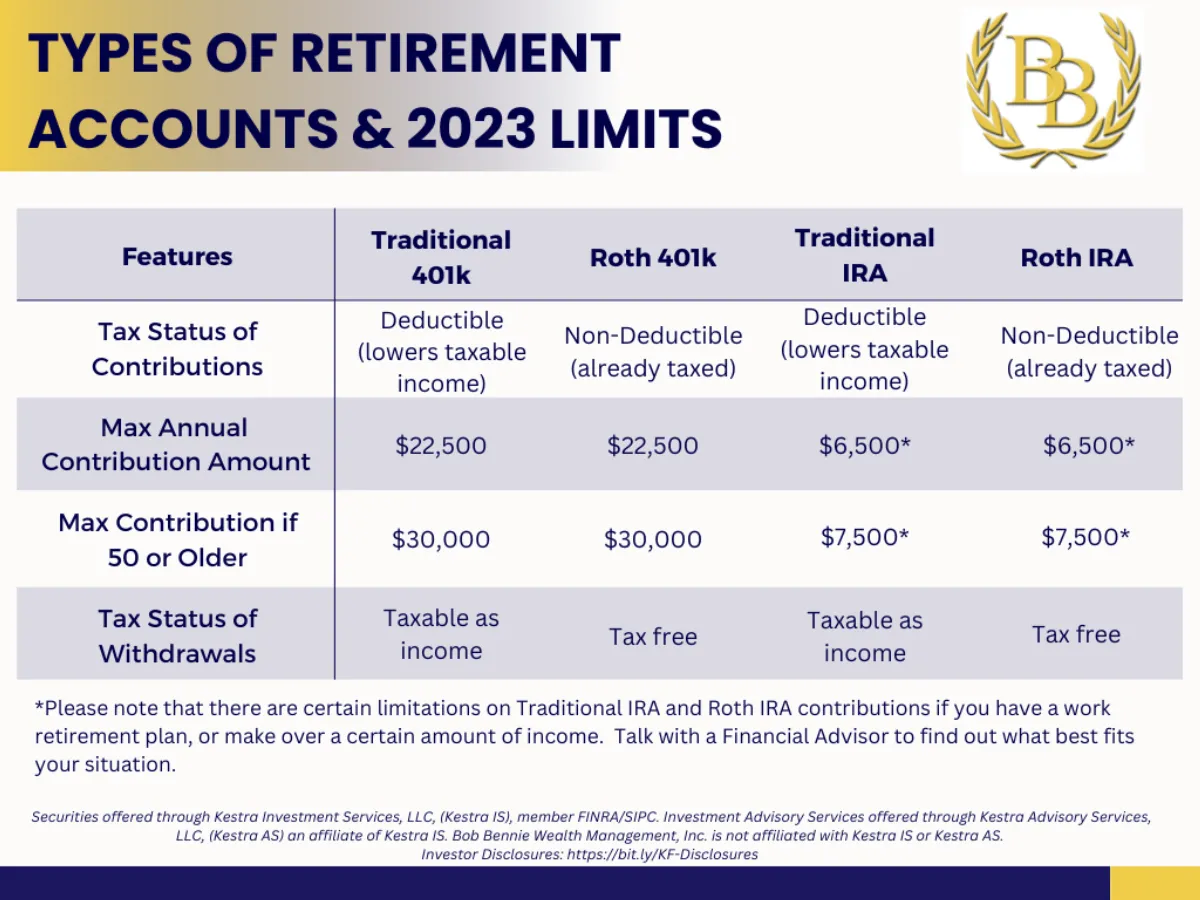
Ah, the 401(k)—the workplace workhorse that your boss probably signed you up for while you weren’t looking. It’s like a forced savings party, but the punch bowl is full of pre-tax dollars. Your contributions lower your taxable income right now, which feels like finding a tenner in an old coat.
Here’s the kicker: many employers will match your contributions up to a certain percentage. That’s free money, folks—like finding a unicorn that poops gold coins. Never, ever leave that match on the table; that’s like refusing a free pizza because you’re “watching your carbs.”
Must Read
Surprising fact: The most common employer match is 4% to 6% of your salary. If you skip that, you’re basically setting a hundred-dollar bill on fire to toast a marshmallow.
The Catch (Because There’s Always a Catch)
You pay income tax when you eventually withdraw the money in retirement. Uncle Sam isn’t giving you a gift; he’s letting you borrow the tax money interest-free. And if you pull cash out before age 59½? You’ll pay a 10% penalty plus taxes. It’s the financial equivalent of getting a parking ticket while your car is on fire.
The Solo Adventurer: The Traditional IRA
The Traditional IRA is like a 401(k)’s slightly less popular cousin who shows up alone to parties. You open it yourself—no job required, no boss’s permission needed. Contributions are often tax-deductible, so you can lower your tax bill again.
But here’s the wild part: in 2024, you can only contribute $7,000 per year (or $8,000 if you’re over 50). That’s like trying to fill a swimming pool with a garden hose, but hey, every drop counts. And yes, the early withdrawal penalty still applies, so don’t treat it like a piggy bank for a spontaneous trip to Fiji.
 How to Create a Financial Plan for Your Retirement - blog.indotim.net
The Surprise Twist: Income Limits
If you’re a high roller making over $87,000 (single) or $143,000 (married filing jointly), your Traditional IRA deduction starts to disappear. It’s like the IRS saying, “You’re too rich for our discount, pal.” So check your income before you get too attached.
The Future You’s Hero: The Roth IRA
Now we’re talking—the Roth IRA is the coolest kid in the retirement club. You pay taxes on the money now, then let it grow tax-free forever. When you pull it out in retirement? Zero tax, zero drama, zero penalties on earnings after age 59½. It’s like building a time machine that sends your money to your future self without the IRS ever asking for a tip.
You can even withdraw your contributions (not earnings) at any time, no penalty. That’s right—you can raid your Roth for an emergency without the IRS chasing you with a pitchfork. It’s the Swiss Army knife of retirement accounts.
The Fine Print (Because Life Isn’t Fair)
Income limits apply here too. In 2024, if you’re single and make over $161,000, you can’t contribute directly to a Roth IRA. There’s a workaround called a “backdoor Roth IRA,” but it’s about as simple as assembling IKEA furniture without the instructions. You’ve been warned.
 Types of Retirement Accounts and Plans
The Underdog: The SEP IRA
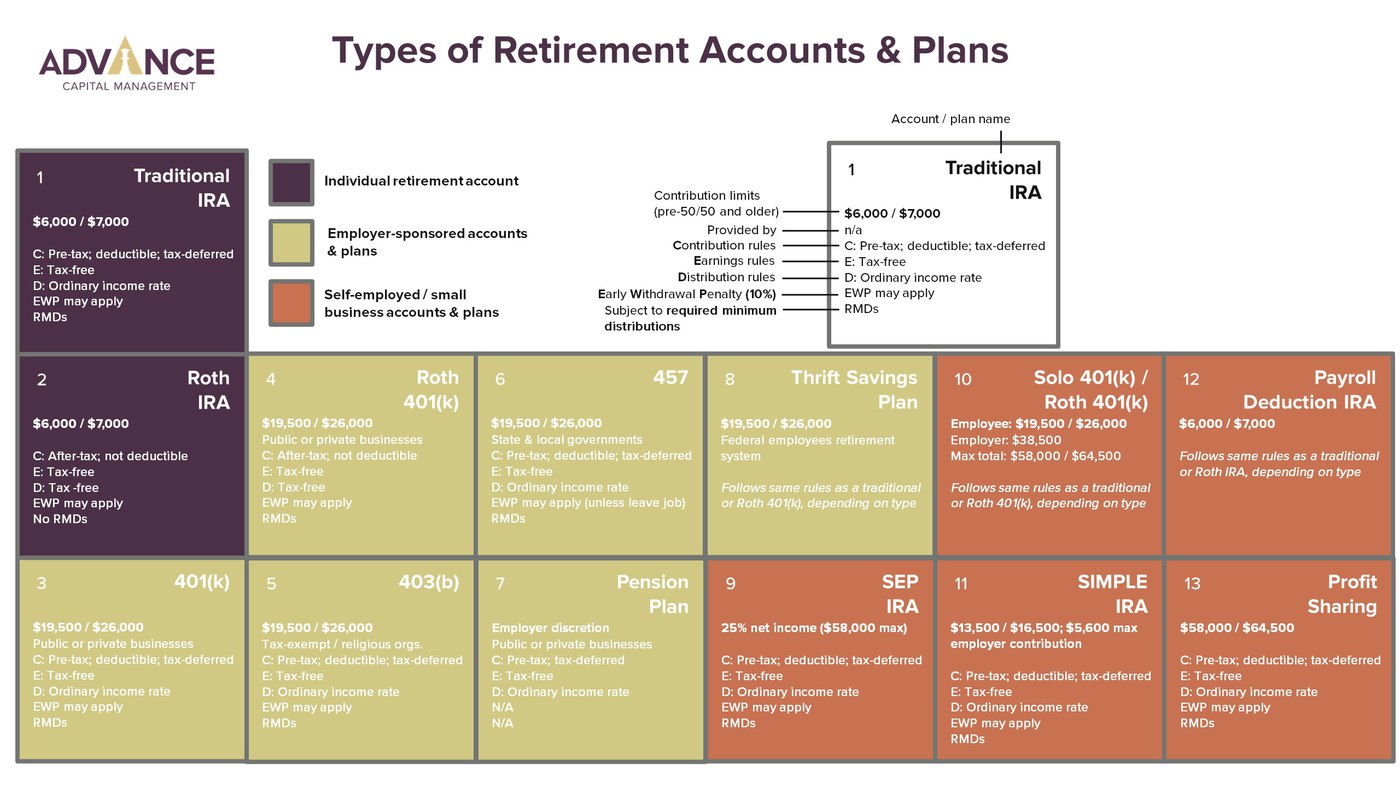
If you own a business or freelance, meet the SEP IRA—the “Simplified Employee Pension” that’s anything but simple. You can contribute up to 25% of your net earnings, capped at $69,000 in 2024. That’s a lot of blenders if you sell blenders.
The goofy part: you must contribute the same percentage for all eligible employees. So if you’re feeling generous and give yourself 20%, your part-time assistant gets 20% too. It’s like accidentally buying dinner for the whole table when you only wanted a side of fries.
The Bottom Line (Finally)
In the great retirement account showdown, Roth IRAs win for flexibility and future tax savings. 401(k)s win for easy, automated saving and that sweet employer match. Traditional IRAs are fine if your income is moderate and you want a tax break today. And SEP IRAs are for people who like getting paid in tax deductions and paperwork.
Remember this golden rule: if you’re young and expect to be richer later, choose Roth. If you’re old, broke, or think taxes will go down, pick Traditional. If you’re confused, do both—diversify your tax bets. It’s called a “ladder” strategy, and it’s fancy enough to impress your friends at brunch.
And finally, a surprising fact to scare you into action: The average retiree spends $4,000 a month on healthcare alone. That’s $48,000 a year for pills and checkups. So go open that account, even if it’s just $20 a month. Your future self is begging you, and he’s not above using guilt—he’s old and cranky.
