Asc 842 Financial Statement Presentation Example

Okay, let's be real for a second: accounting standards usually sound about as fun as watching paint dry. But ASC 842? That’s the lease accounting rule that turned every office...
Okay, let's be real for a second: accounting standards usually sound about as fun as watching paint dry. But ASC 842? That’s the lease accounting rule that turned every office chair and copier into a dramatic courtroom exhibit. Today, we’re going to walk through a financial statement presentation example without needing a nap or a glass of wine. Grab your favorite mug—let’s dive in.
The Big Shift: Why ASC 842 Even Exists
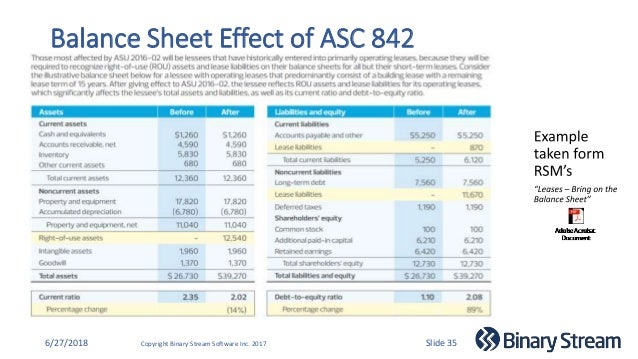
Before 2019, companies could hide their biggest rental obligations in the footnotes like a guilty secret. ASC 842 came along and said, “Nope, put it on the balance sheet.” Now, almost every lease—from a warehouse to a delivery van—gets a shiny new Right-of-Use (ROU) asset and a lease liability. It’s like moving from a messy closet to a glass house. Every sock is visible.
This change wasn’t just about transparency—it was about trust. Investors wanted to see the real picture, not the airbrushed version. So, let’s look at how that picture actually gets painted on the financial statements.
Must Read
Meet Our Example: "Lemonade Leasing Inc."
Imagine you’re helping your friend’s company, Lemonade Leasing Inc., which rents out bright yellow lemonade stands. They sign a 5-year lease for a prime corner lot at $1,000 a month. That’s a total of $60,000 in undiscounted payments. Fun math time!
We’ll use a 5% incremental borrowing rate (because Lemonade’s credit score is decent, thanks to all that citrus). When you calculate the present value, the lease liability lands at about $52,895. The ROU asset? Usually, it’s the same value, maybe plus initial costs like a deposit for the lemon squeezer.
Where It Shows Up on the Balance Sheet
Here’s where the magic happens. On the balance sheet, you’ll see two new items. First, in the non-current assets section: “Right-of-Use Asset – Operating Lease” for $52,895. Second, in the liabilities section, you split the lease liability. The portion due within one year (say $10,000) goes under current liabilities. The rest—$42,895—sits in non-current liabilities.
Don’t panic at the split. It’s just accounting’s way of saying, “Hey, you owe some cash next year, and the rest later.” Your friend’s balance sheet just grew a few inches, but it’s healthy growth—like a plant that finally gets sunlight.
The Income Statement Dance
Now, let’s waltz over to the income statement. For operating leases, you don’t see the lease liability directly. Instead, you record a single lease expense. This is a straight-line cost, so Lemonade reports $12,000 every year ($1,000 × 12 months) as a rent expense. It’s usually tucked into Selling, General & Administrative (SG&A) costs.
 Q&A from ASC 842: An Introduction to Lessee Accounting Webinar - GAAP
Here’s a sneaky detail: interest expense on the lease liability is embedded in that single line. You don’t separate it like with a finance lease. So, the income statement looks simpler, but it’s doing a little juggling act behind the scenes. Profit? Still lemonade-scented.
The Cash Flow Statement: The Unsung Hero
Don’t forget the cash flow statement. This is where things get beautifully logical. Every lease payment is split into two parts. The principal reduction (paying down the liability) is shown as a financing activity. The interest portion is an operating activity.
So, for Lemonade’s first payment of $1,000, about $220 goes to interest (operating), and $780 reduces the liability (financing). It sounds messy, but it actually matches reality: you’re paying for the use of the lot (operating) and slowly buying down your debt (financing). Your friend’s CFO will look like a genius at the next board meeting.
Common Pitfalls (and How to Laugh Them Off)
Mistake number one: forgetting to re-measure the lease when you renew early. If Lemonade renegotiates for a cheaper rate, you have to update the ROU asset and liability. It’s like realizing your favorite lemonade stand has a coupon—you adjust everything.
Another classic: mixing up short-term leases (12 months or less) that you can elect to keep off the books. If Lemonade rents a cart for 11 months, no ASC 842 drama. But if it’s 13 months, you’re back in the ROU game. Always read the fine print—or your lease term.
 PPT - ASC Topic 842: “Leases” PowerPoint Presentation, free download
And finally, don’t forget disclosures. The footnotes need to explain your lease term, discount rate, and maturity analysis. It’s not just paperwork—it’s your chance to tell a story. “Our fleet of lemonade stands is growing, folks!”
Why This Actually Matters (Yes, Really)
ASC 842 isn’t about making accountants happy (though it does). It’s about giving investors a clear view of your commitments. When Lemonade’s balance sheet shows $52,895 in lease liability, lenders know you’re not hiding debt under a rug. Transparency builds trust.
Plus, this standard helps you plan. Seeing those liabilities in black and white might push your friend to buy the lemonade lot instead of lease it. Or maybe they’ll negotiate shorter terms. Either way, you’re the hero who made sense of the numbers.
The Uplifting Conclusion: You Did It!
Look at you! You just walked through a whole ASC 842 example without needing a single aspirin. You now know that ROU assets and lease liabilities are just fancy names for “I owe a lot of lemons, but I’ll pay them back.” Your balance sheet is a little heavier, your income statement a little simpler, and your cash flow statement is doing the cha-cha.
So next time someone mentions ASC 842 at a party, you can smile knowingly. You’ll say, “Oh, the lease standard? Yeah, I helped a lemonade company sort that out.” And you’ll feel like an absolute rock star—because you are. Accounting isn’t just numbers; it’s the recipe for clarity and confidence. Now go celebrate with a cold glass of lemonade. You’ve earned it.
