U.s. Treasury Yield Curve Movements 2024 Summary

The Year the Yield Curve Un-Inverted (And Why You Should Care) If you spent 2024 scrolling past headlines about the U.S. Treasury yield curve, you weren’t alone. It sounds li...
The Year the Yield Curve Un-Inverted (And Why You Should Care)
If you spent 2024 scrolling past headlines about the U.S. Treasury yield curve, you weren’t alone. It sounds like something only a financial wizard in a bow tie would care about—but trust us, it’s the quiet soundtrack to your mortgage rate, your 401(k), and that awkward conversation about the economy at brunch. The yield curve did a backflip this year, moving from a screaming warning signal to a surprisingly calm exhale. Let’s unpack it like we’re catching up over coffee, not a quarterly report.
The Plot: Everyone’s Favorite Inversion Party
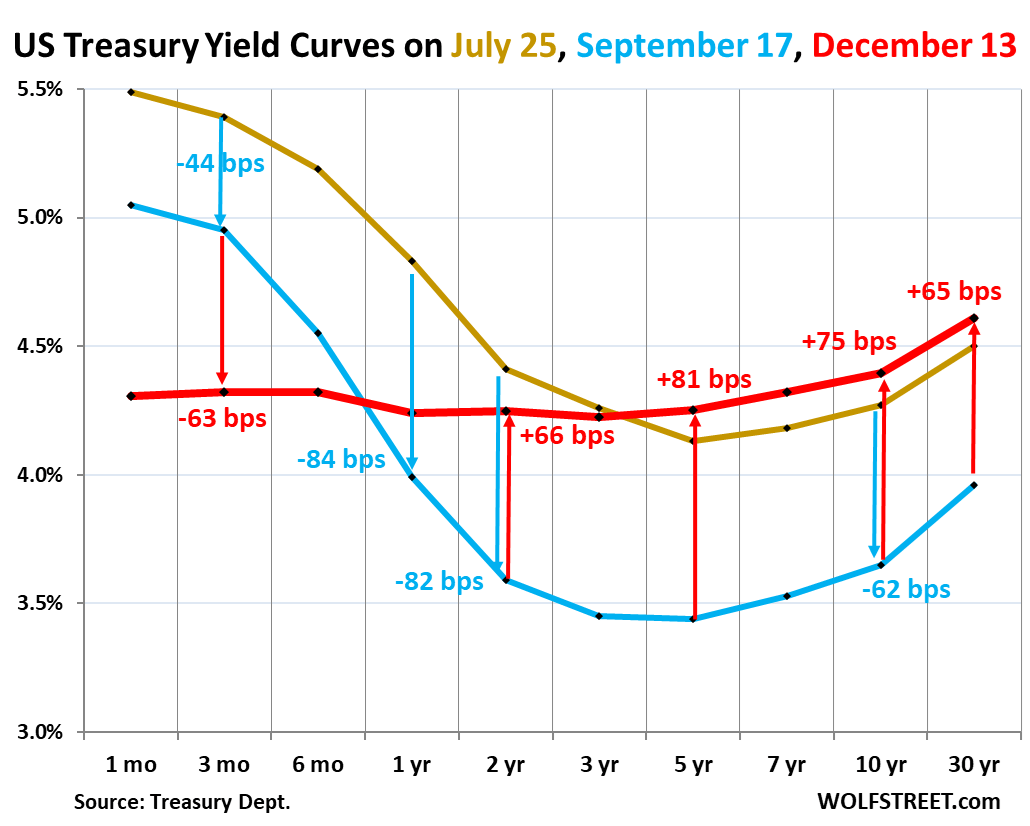
Remember when everyone panicked about an “inverted yield curve” in 2022 and 2023? That’s when short-term bonds paid more than long-term ones—a weird, upside-down scenario that has historically predicted recessions. In 2024, that curve finally un-inverted, meaning the 10-year Treasury note started paying more than the 2-year note again. It’s like the economic world took a deep breath and sat down.
Think of it this way: normally, you want more money for lending your cash longer (that’s the “normal” slope, like an escalator). An inverted curve was the escalator running backwards. For most of 2024, the curve went from “yikes, get off” to “okay, we can walk.” The un-inversion started in earnest around September, after the Federal Reserve cut interest rates for the first time in four years. It was the market’s way of saying, “Maybe the fall won’t be so hard.”
Must Read
The Cast: Characters That Drove the Plot
Let’s meet the key players. First, the 10-year Treasury yield, the VIP of the bond world—it sets the vibe for mortgages and corporate loans. It started 2024 around 3.9%, flirted with 4.7% in April (because of stubborn inflation), then settled near 4.2% by December. That’s not a rollercoaster, but it’s a solid B-plot.
Then there’s the 2-year yield, the jittery friend who reacts to every Fed whisper. It fell faster than the 10-year, dropping from 5% in January to under 4% by year-end. That gap—the spread between them—is the show. It went from deeply negative (inverted) to barely positive (normal-ish) by fall. Fun fact: the curve spent a record 783 days inverted before it snapped back. That’s longer than your average sitcom series.
What Actually Happened: A Quarterly Breakdown
Q1 2024: The Hangover. The curve was still inverted, and inflation data kept everyone guessing. The 10-year hovered around 4.2%, while the 2-year stubbornly clung to 4.9%. Nobody was buying party hats.
Q2: The Drama Spike. A surprise inflation uptick in April sent the 10-year yield north of 4.7%. Bond traders screamed into their keyboards. But then, like a plot twist in a rom-com, inflation cooled in May and June, and yields slid back. The spread narrowed, but the curve stayed inverted. It was the “will they, won’t they” of finance.
 Mortgage Rates Explode, 2-Year & 10-Year Treasury Yields Spike, Monster
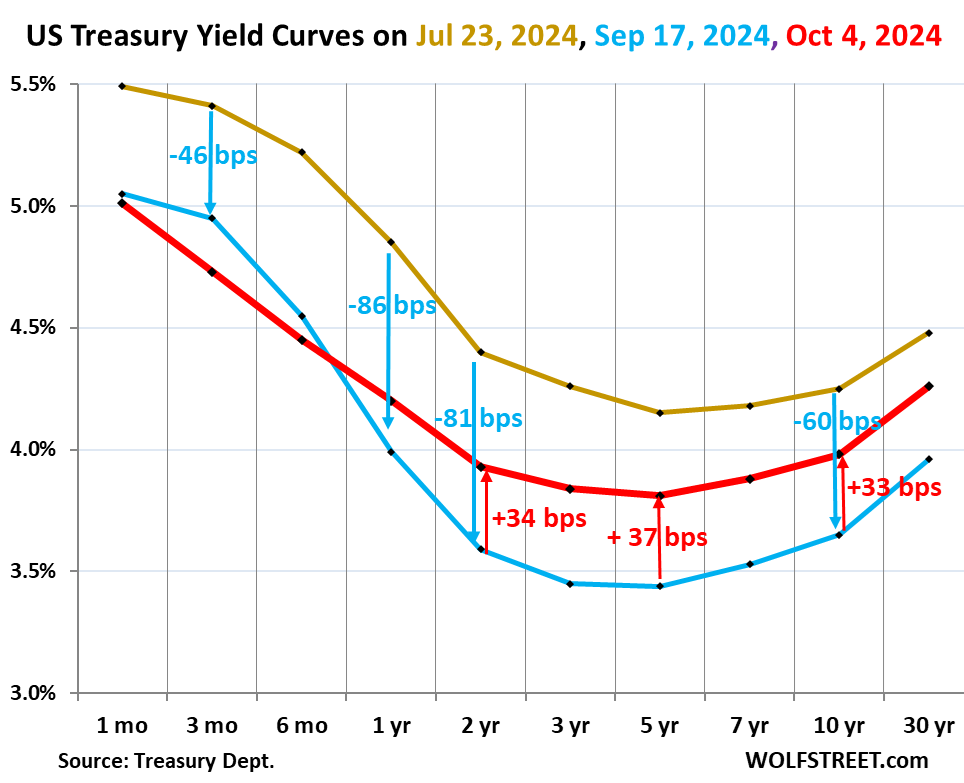
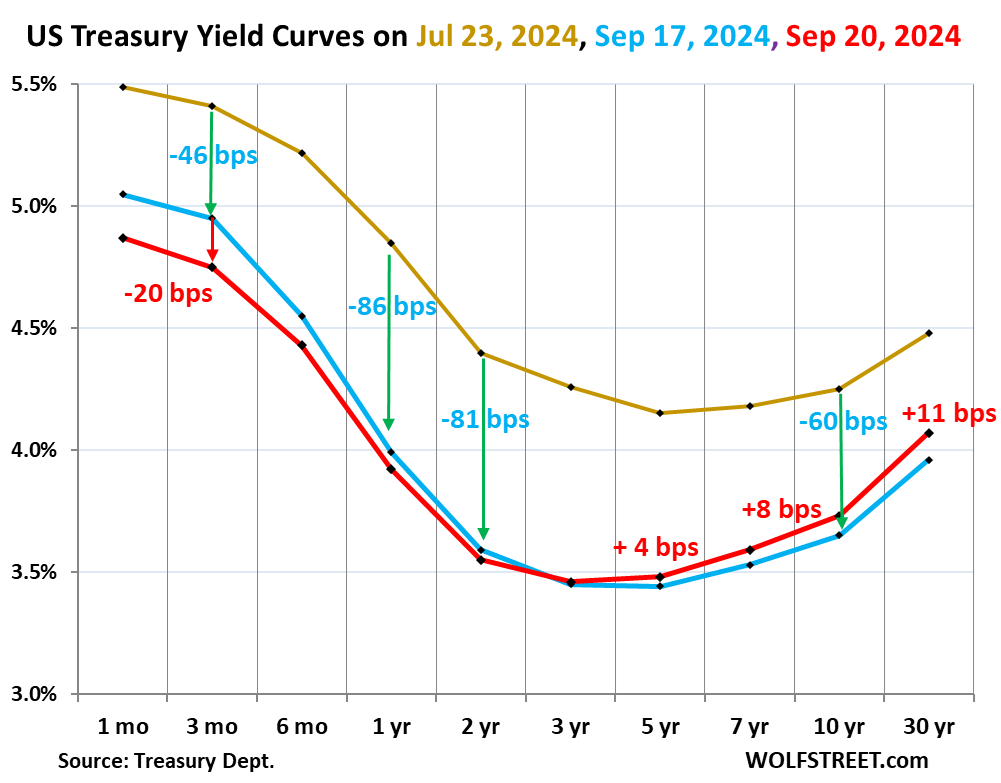
Q3: The Big Un-Inversion. This is the season finale. The Fed cut rates by 50 basis points in September—a double-shot espresso move. Suddenly, short-term yields dropped like a hot mic, while long-term yields stayed steady. The curve officially went positive for the first time since July 2022. Financial Twitter had a field day. Practical tip: if you saw mortgage rates drop a touch in October, thank this moment.
Q4: The Steady Sigh. The curve stayed upward-sloping but shallow. The 10-year ended near 4.2%, and the 2-year near 3.9%. It’s not a booming recovery, but it’s not a crash landing either. Think of it as a “we’re fine, let’s keep the music on” vibe.
Why It Matters for You (Yes, You)
Here’s where the yield curve touches your life. When the curve is inverted, banks get nervous about lending, which means credit cards, car loans, and mortgages get pricier. A normal curve makes borrowing cheaper—but only if the economy is stable. In 2024, the un-inversion didn’t trigger a party; it just stopped the bleeding.
Practical tip for 2025: If you’re shopping for a home or refinancing a student loan, watch the 10-year yield. It usually moves first. A dip below 3.8% could signal a sweet spot. Conversely, if it jumps above 5%, lock in rates fast—the curve might get spiky again.
 The Yield Curve Before & After the Rate Cut: Why Have Longer-Term
Fun little fact: the yield curve has predicted every recession since the 1950s, but it also once gave a false alarm in 1966. So it’s a rock star, but a temperamental one. It’s also the only economic indicator that people actually make memes about (search “yield curve bulge meme” if you need a laugh).
Cultural Checkpoints: What the Curve Was Saying
Think of the yield curve as the economy’s body language. In 2024, it started the year hunched over, fists clenched. By fall, it had unrolled its shoulders and taken off the armor. It wasn’t dancing yet, but it was nodding along to the new Chappell Roan album.
The un-inversion happened alongside the rise of “AI fatigue” in markets and electric vehicle stock dramas. It also reflected a world where everyone was waiting for a recession that didn’t come—kind of like waiting for a sequel that keeps getting delayed. The curve’s message? “We’re not out of the woods, but at least we can see the trailhead.”
A Short Reflection for Your Daily Life
Here’s the takeaway for your Sunday morning coffee scroll: the yield curve is a mirror of collective fear and comfort. When it inverts, we brace; when it un-inverts, we exhale. But life doesn’t wait for bond traders to finish their calculus. You can check the 10-year yield once a month—it’s free on your phone’s weather app or any financial site—and treat it like a weather report for your wallet. Sunny? Go ahead and plan that vacation. Cloudy? Maybe stash a little extra cash.
In 2024, the curve reminded us that even the weirdest, most inverted loops eventually straighten out. It’s a metaphor, really. Your own life curve—job moves, relationships, weird surprises—can invert, too. But it always finds a way to slope upward again. So breathe. Buy the bond or buy the oat milk latte. Either way, the yield curve is just the background music. You’re the lead singer.
