Calculating Inflation Using Consumer Price Index

So, my buddy Mark texted me the other day: “Remember that pizza joint we loved in college? I just paid $18 for a large pepperoni. Eighteen bucks! Are they using truffle oil no...
So, my buddy Mark texted me the other day: “Remember that pizza joint we loved in college? I just paid $18 for a large pepperoni. Eighteen bucks! Are they using truffle oil now, or did the dollar just decide to hit the gym?” I laughed, but then I looked at my own grocery receipt. That $5 block of cheddar? Now it’s $7.50. I felt a little less like laughing.
That feeling? That’s inflation, baby. And it’s not just a conspiracy theory from your uncle on Facebook. It’s the slow, sneaky way your money buys less than it used to. But how do we actually measure this chaos? That’s where the Consumer Price Index—or CPI, for the cool kids—waltzes in.
What Even Is the CPI?
Think of the CPI as the government’s official shopping list. It’s a basket of stuff the average American buys: milk, gas, rent, Netflix subscriptions, dental floss, and—yes, probably—overpriced pizza. Every month, economists check the price of this exact basket. They don’t just eyeball it—they track thousands of items in 75 urban areas.
Must Read
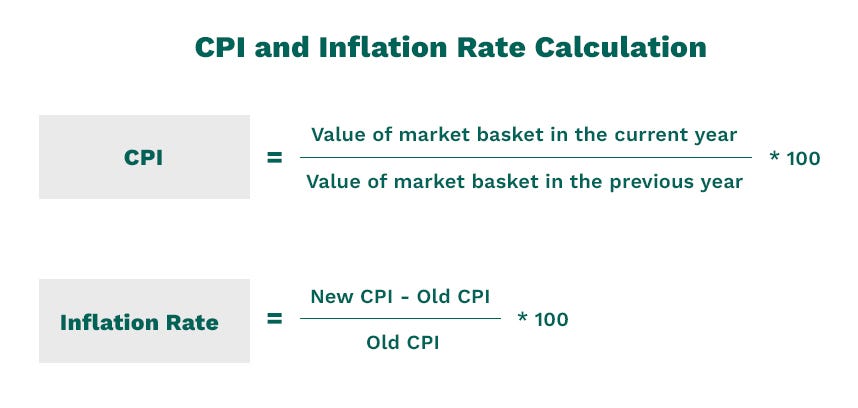
Then, they compare the current total cost of that basket to what it cost in a “base year” (like 1982–1984, which I’m pretty sure is when gas was a nickel and a handshake paid for your house). The result? A percentage that tells us how much prices have bounced up or down. That percentage is inflation. That’s it. No magic, just math—and a lot of clipboard-wielding data nerds.
The Basket: Not Your Grandma’s Groceries
Here’s the ironic part: the basket changes. If everyone suddenly swapped steak for oat milk and avocado toast, the CPI basket shifts too. Smart, right? But it also means your personal inflation might be totally different from the official number.
For example, if you’re a landlord who drives a Tesla and only buys organic kale, your “basket” is spicy. If you’re a broke college kid living on ramen and bus passes, your basket is just sad. The CPI is an average, not a crystal ball for your wallet. So when the news says “inflation is 3%” and you swear it’s 10%, you’re probably both right. (See? Even data is subjective. Welcome to modern economics.)
How the Magic Calculation Works
Ready for a little math? Don’t panic. It’s more like following a recipe. First, they pick the basket and weight each item. Housing gets the biggest slice of the pie (over 30%), because rent or mortgage hurts the most. Then, they assign smaller weights to food, gas, and—I assume—avocado toast.
 Steps To Calculate Inflation Using Consumer Price Index Inflation
Let’s say in the base year, the basket costs $100. This year, it costs $108. You do the math: (108 – 100) / 100 x 100 = 8% inflation. That’s it. Now, do that across 5,000+ items with shifting weights, and you’ve got the CPI. It’s like baking a soufflé while riding a unicycle, but the Bureau of Labor Statistics makes it look easy.
(Side note: There’s also “Core CPI,” which strips out food and energy because those get volatile. You know, like when a hurricane in Florida sends orange juice prices to the moon. Core CPI is the chill, optional version of the index.)
The Glaring Flaws (Because Nothing’s Perfect)
Okay, let’s be real: the CPI isn’t your life. If you’re a retiree on a fixed income who spends huge on medical bills, the CPI’s 3% feels like a joke. Inflation hits different groups differently. The index also struggles to measure quality changes. Your new iPhone costs more than the old one, sure—but it also has a camera that could land a Netflix special. Does the CPI fully adjust for that? Debatable.
There’s also the “substitution bias.” If beef gets crazy expensive, you might buy chicken instead. The CPI basket tries to account for this by updating items periodically, but it’s a little slow. By the time they swap out the VCR for a streaming subscription, you’ve already canceled Netflix. Oops.
 Steps To Calculate Inflation Using Consumer Comprehensive Guide On Inflatio
Why Should You Care? (Other Than Feeling Poor)
Here’s the real tea: the CPI affects your paycheck. Social Security, pensions, and even your salary raises are often tied to it. Your boss might give you a 2% raise and say, “Inflation is low!” But if your rent just jumped 10%, that raise is actually a pay cut. The CPI helps you argue for more—or at least understand why your landlord is laughing.
Investors also use the CPI to adjust bond yields and retirement accounts. If you’ve got a 401(k), the CPI decides whether your savings are actually growing or just choking on inflation. Knowing how the number is cooked gives you power—or at least makes you sound smart at parties.
The Bottom Line (With a Side of Sarcasm)
So next time Mark texts you about $18 pizza, you can reply: “That’s just the CPI’s ‘Food at Home’ category, weighted at 13.4%, with a 0.2% seasonal adjustment. But yeah, it’s still robbery.” And then you’ll realize the CPI is a tool—helpful, flawed, and totally necessary. It doesn’t capture your specific struggle, but it gives us a common language to yell about who’s robbing us blind.
Now go check your wallet. I’ll wait. And maybe skip the extra cheese.
