Property And Casualty Insurance Exam Cheat Sheet

So, you’re studying for the Property and Casualty insurance exam. First off, let me just say: I’m so sorry about your social life. You’ve been replaced by flashcards and a ver...
So, you’re studying for the Property and Casualty insurance exam. First off, let me just say: I’m so sorry about your social life. You’ve been replaced by flashcards and a very lonely coffee mug.
But don’t worry! I’m here to hand you the ultimate cheat sheet—minus the actual cheating, because insurance regulators have a sixth sense for that. Think of this as a mental shortcut, a friendly map through the jungle of policy jargon.
We’re going to make this fun. Or at least, we’ll try. Grab your lucky pen, and let’s dive into the chaos together.
Must Read
1. The Big Two: Property vs. Casualty
Here’s the golden rule you’ll hear over and over: Property covers stuff, Casualty covers stupid things you do. Property insurance = your house, your car, your prized collection of rubber ducks.
Casualty (which includes liability) = when you accidentally back your car into your neighbor’s mailbox. (And then lie about it, but don’t tell your underwriter that.)
Remember: Property protects things. Casualty protects your wallet from your own mistakes.
2. Perils, Hazards, and the “Act of God” Excuse
A peril is the actual event that causes damage—like a fire, a tornado, or your uncle’s terrible cooking. A hazard is a condition that makes that event more likely—like leaving a greasy rag in the garage (that’s a physical hazard).
Then there’s the moral hazard: when you secretly hope your old couch burns down so you can buy a new one. Don’t test that one, by the way. Adjusters are suspicious people.
And finally, “Act of God”—that’s the insurance industry’s polite way of saying, “We’re not paying for that volcano, sorry.”
3. The Policy Structure (Think of It Like a Sandwich)
Every policy has four parts, and the exam loves to quiz you on them. Picture your favorite deli sandwich.
Declaration Page: The bread. It lists who you are, what you’re insuring, and how much you’re paying. No bread, no sandwich.
Insuring Agreement: The meat. This is the promise: “We’ll pay if X happens.” It’s the whole reason you’re here.
Conditions: The lettuce and tomato. The rules you have to follow, like reporting a claim within 24 hours. Mess this up, and your sandwich falls apart.
Exclusions: The pickles nobody wanted. “We cover flood damage—unless you live in a bathtub.” Actually, floods are almost always excluded. Cue sad trombone.
4. Key Terms That Sound Like Made-Up Words
Indemnity: The fancy term for “we put you back where you were before the disaster.” You don’t get a profit. You get your same old couch, but clean.
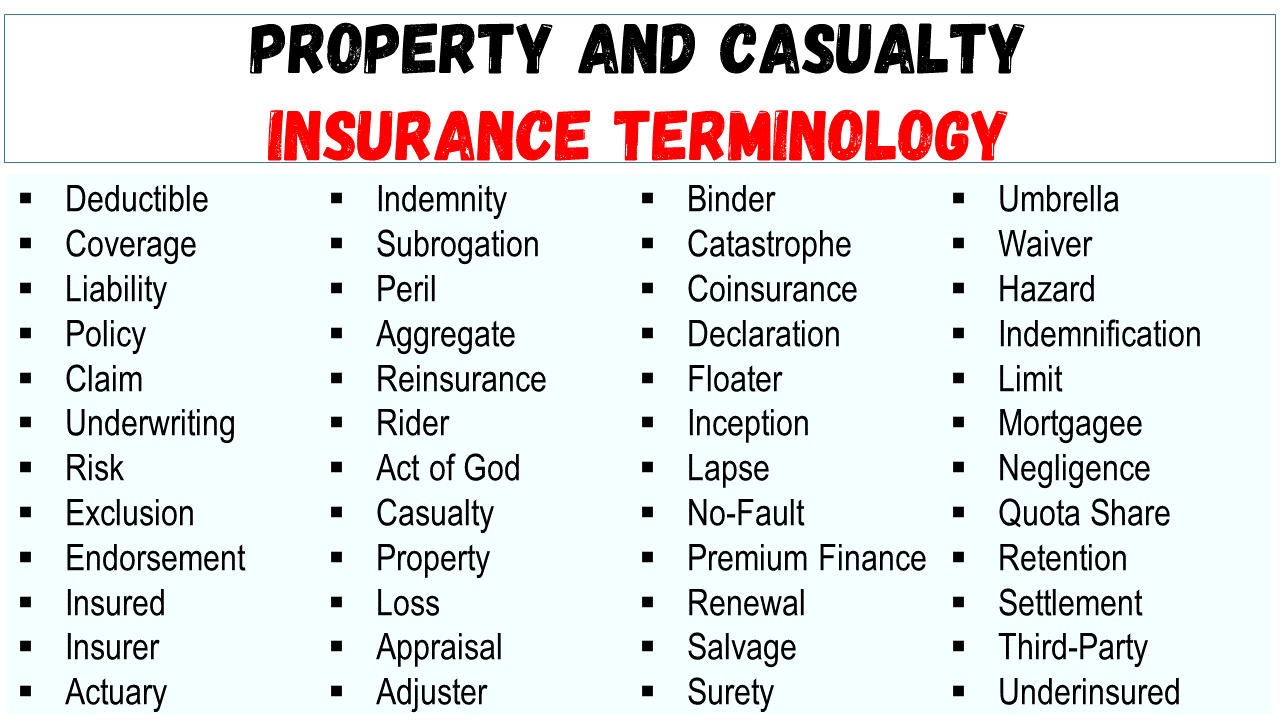 Property and Casualty Insurance Terminology (Download PDF) - EngDic
Deductible: The part of the damage you pay first. If your deductible is $500 and the damage is $501, you pay $500. Congratulations, you “saved” a dollar. (Kind of.)
Coinsurance: This is a trap. If you underinsure your house (say, only 70% of its value), the insurer punishes you by paying less on a claim. It’s like being grounded for not cleaning your room—mean, but legally allowed.
5. The “Named Peril” vs. “Open Peril” Smackdown
A named peril policy covers only the disasters specifically listed—like fire, wind, and hail. If a meteorite crushes your shed, sorry, you’re out of luck. (Unless “meteorite” is on the list, which it isn’t.)
An open peril policy covers everything except what’s excluded. It’s much broader. Example: “We cover damage from a falling piano—unless we specifically wrote ‘no pianos.’”
On the exam, remember: Named = narrow. Open = optimistic (for you).
6. Distracted Driving and the “ROTH” Acronym
For auto insurance, watch out for the term “ROTH.” It stands for: Reasonable Operation of a Technical Hazard. Wait, no. That’s not right.
Actually, just remember “PERIL” for auto: Policy, Exclusions, Restrictions, Insuring agreement, Limits. I made that up, but it sounds official. The real trick is to know that “collision” covers hitting a tree, while “comprehensive” covers theft, vandalism, or a deer giving your car a hug.
And yes, hitting a deer is comprehensive. Deer are considered “wild animals,” not “your fault.” Finally, nature takes the blame.
7. Workers’ Comp and the Magic Phrase “Course of Employment”
If an employee gets hurt while working, it’s covered. If they get hurt while nap-battling the office cat during lunch, the lines get blurry. The exam loves to test this gray area.
Key phrase: “Arising out of and in the course of employment.” Memorize it. Say it in the mirror. It’s your free pass for a few points.
Also, workers’ comp is a no-fault system. Translation: even if the employee was juggling chainsaws against company policy, the insurance still pays. The boss just fires them later.
8. The “Reservation of Rights” Letter (Don’t Panic)
If an insurer sends you a reservation of rights letter, it’s not a breakup. It’s a polite way of saying, “We’ll pay for now, but we’re not 100% sure we have to.” It protects their right to deny the claim later if they find out you hid a pet tiger in the garage.
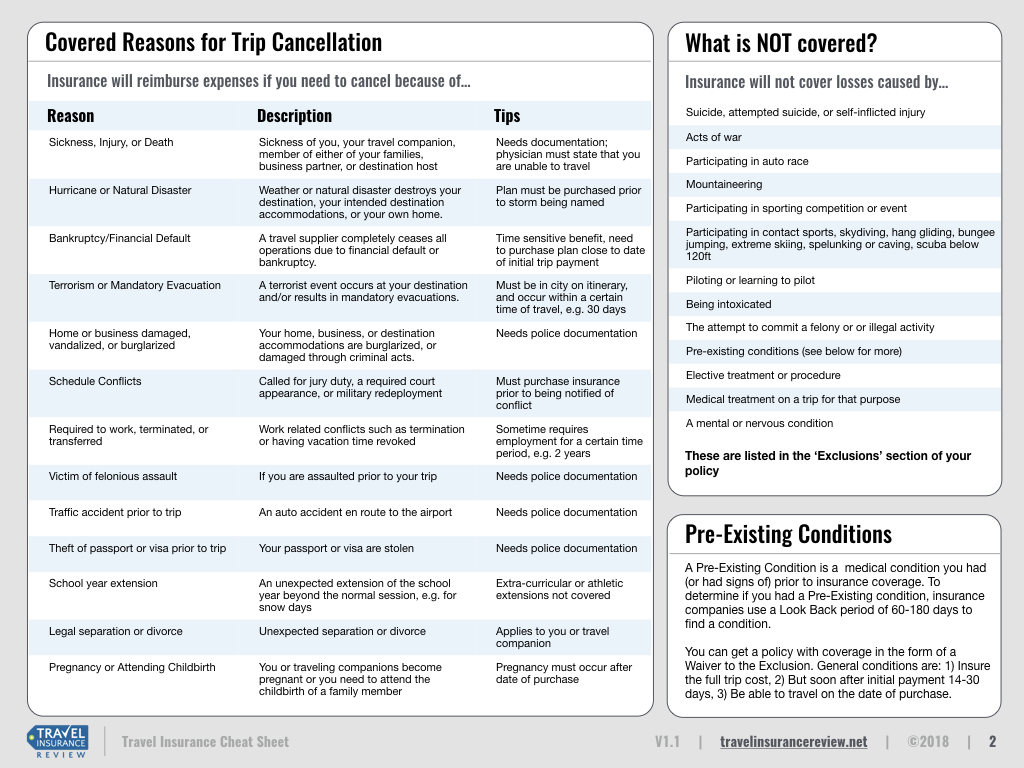 Insurance Terminology Cheat Sheet – VYWSOB
On the exam, remember: “ROR” means “Relax, Our Researcher” is working on it. Actually, it means they’re keeping their options open.
Pro tip: never hide a pet tiger. It’s always excluded.
9. The 5-Minute Cram Memory Hacks
Use this silly mnemonic: “CLUE” stands for Coverage, Limits, Underwriting, and Exclusions. But you already knew that.
For agents vs. brokers? An agent represents the insurance company. A broker represents you. Pretend the agent is the barista who makes your coffee, and the broker is your friend who steals your coffee and complains about the price. (Broker jokes are free.)
And if you ever feel lost, just whisper “utmost good faith” under your breath. It means you have to be honest or the policy is void. Honesty: the cheat code that isn’t cheating.
10. Final Exam-Day Survival Tips
Eat a good breakfast. No, donuts do not count as a vegetable. Get a good night’s sleep—your brain needs to be sharp, not running on fumes and anxiety.
Read each question twice. Once for what it says, once for what it really says. Insurance exam writers are sneaky; they love the word “except.”
And for the love of all that is insurable, pace yourself. You have 90 minutes. It’s not a race. It’s a marathon with a lot of paperwork and a finish line that says “Licensed Professional.”
You’ve Got This
Look, I know this feels like memorizing a phone book written in legal gobbledygook. But here’s the truth: the exam isn’t testing if you’re a genius. It’s testing if you’re careful.
And you? You’re a careful person. You’re reading an article about a cheat sheet for a test about insurance. That’s next-level level responsibility. You’ve already passed the “good attitude” test.
So take a deep breath. Review your notes. Use these shortcuts. And when you sit down in that exam room, remember: Property is stuff, Casualty is your goof-ups, and you are absolutely, 100% ready to crush this.
Now go forth, get licensed, and start telling people you protect them from “acts of God” and bad decision-making. Just don’t mention the part about the deer.
Good luck, you magnificent insurance nerd. You’re going to be amazing.
