Ngpf Compare Types Of Retirement Accounts Answer Key

Let’s be honest: staring at a retirement account comparison chart feels a bit like trying to read a menu in a language you don’t speak—say, ancient Sumerian, but with more tax...
Let’s be honest: staring at a retirement account comparison chart feels a bit like trying to read a menu in a language you don’t speak—say, ancient Sumerian, but with more tax forms. You see words like Roth, Traditional, and 401(k) and your brain just goes, “Please, sir, I just want to retire with a beach hut and a cat.” If you’ve ever Googled “NGPF Compare Types Of Retirement Accounts Answer Key” hoping for a cheat code to adulthood, welcome. You’re my people.
First, let’s clear the air: the NGPF (Next Gen Personal Finance) doesn’t actually give you a magic answer key for life. That would be too easy. But what they do give you is the secret decoder ring for the three big retirement buckets: the Traditional IRA, the Roth IRA, and the 401(k). Think of these as three slightly weird roommates in the house of your future. You need to choose which one gets the good couch.
The Traditional IRA: The “Trust Me, Future You Will Hate Taxes” Plan
Picture this: you put money into a Traditional IRA today, and the government gives you a high-five and a tax deduction right now. That’s not a joke. It’s called pre-tax magic. You shrink your taxable income for the year, which feels great when you’re buying avocados.
Must Read
But here’s the twist—the government is like a friend who spots you cash for a pizza, then shows up fifty years later with a calculator. You pay taxes on every single dollar you withdraw in retirement. Every. Single. Dollar. Including the interest. It’s the financial equivalent of “I’ll pay you back later.” And later, you’ll be crying into your Social Security check.
Surprising fact: if you’re in a lower tax bracket when you retire (which many people are), this is actually a genius move. But if you become a millionaire? The IRS will send you a thank-you card. Probably not, but they’ll definitely cash your check.
The Roth IRA: The “I’m a Tax Badass Now” Option
The Roth IRA is the rebel of the retirement family. You put in after-tax money. That means Uncle Sam takes his cut today, and you get zero tax deduction. It feels terrible. Like paying for a sandwich you don’t eat for thirty years. But here’s the punchline: you never pay taxes again. Not on the gains, not on the withdrawals, not even if you pull out a million dollars to buy a solid gold yacht.
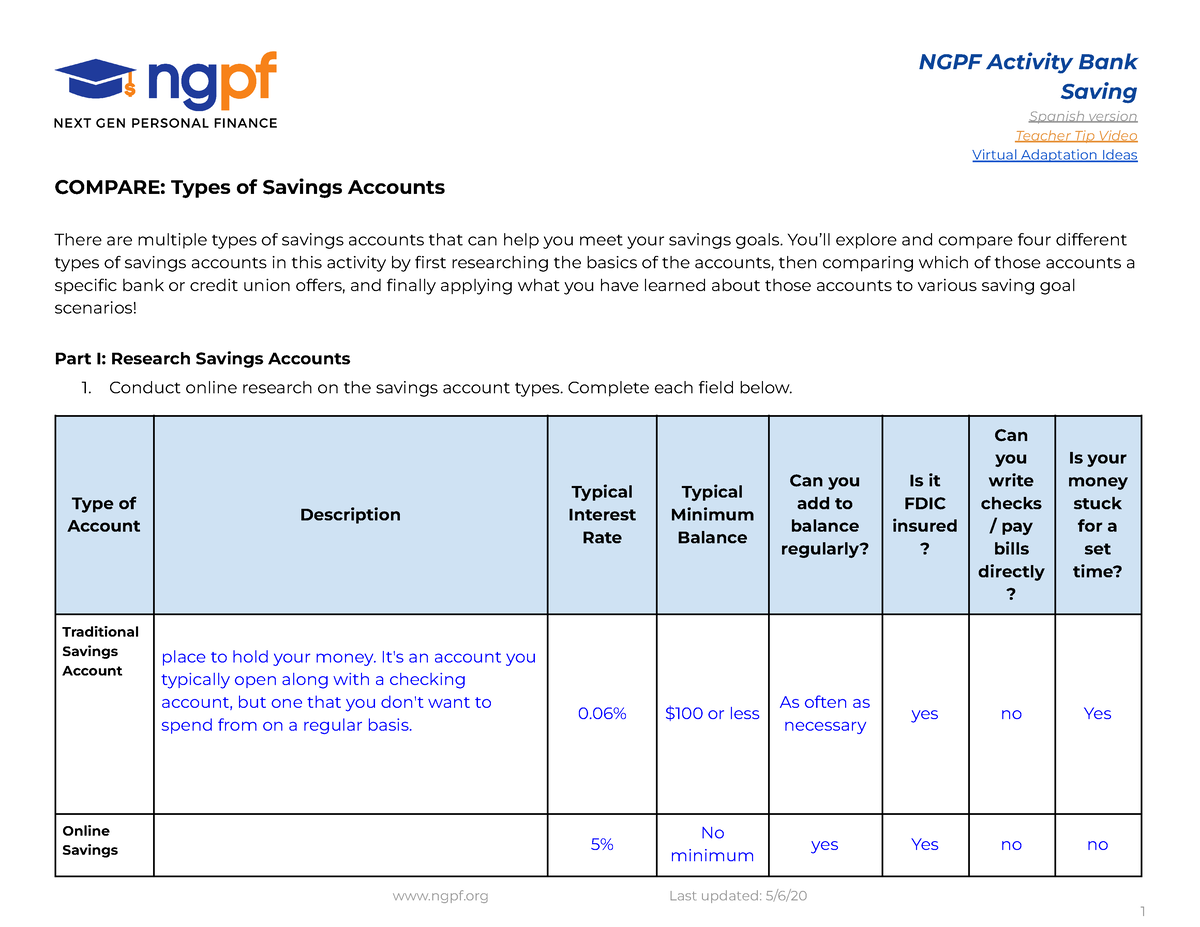
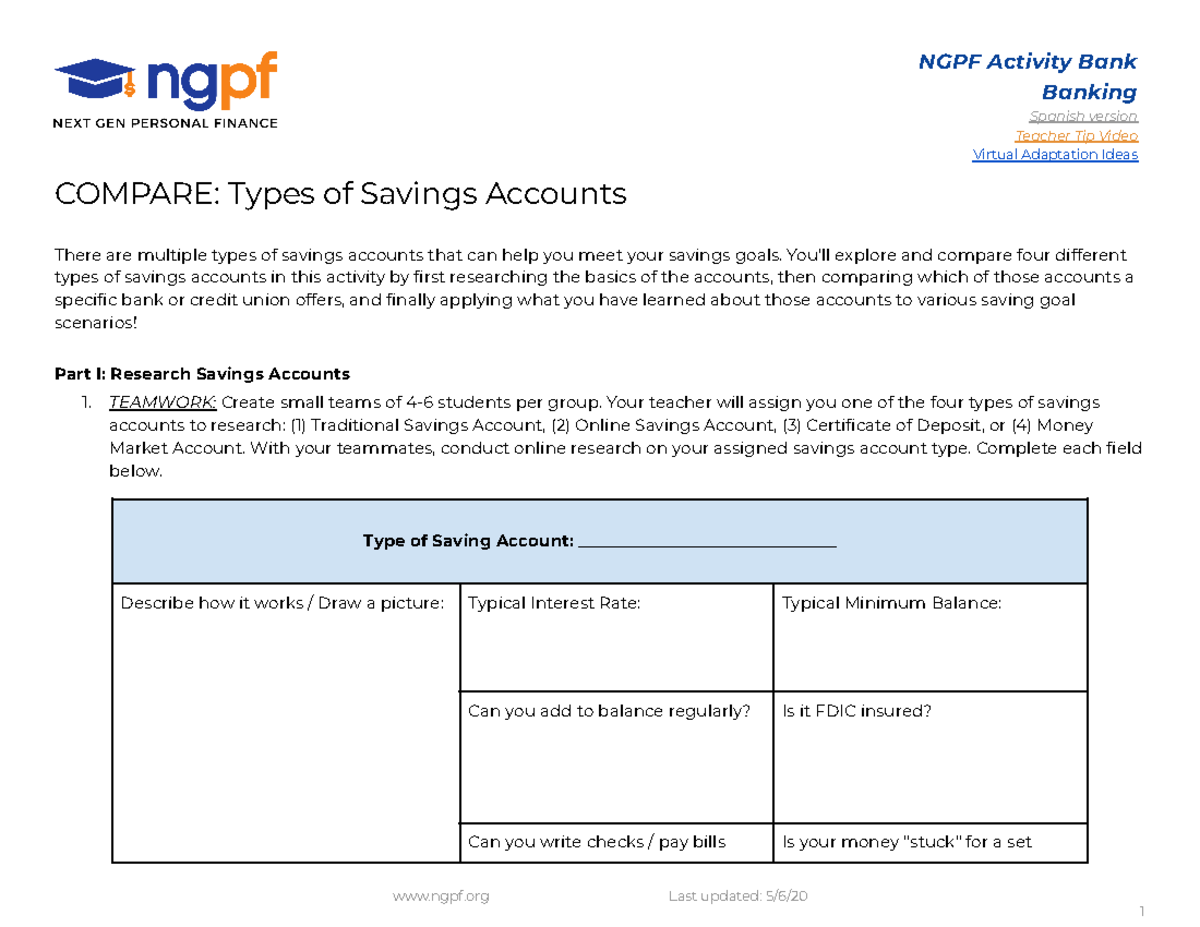 NGPF Activity: Comparing Different Types of Savings Accounts - Studocu
This is the account where the answer key says, “Young people, listen up.” If you are under 30 and you start a Roth IRA, your future self will probably build a statue of you made of compound interest. The max you can put in each year is around $7,000 (as of 2025), which is less than a used Honda Civic. But if you max it out for twenty years, you could end up with a tax-free pile of cash big enough to make a dragon jealous.
And here’s the wild part: you can withdraw your contributions (not the earnings) anytime, tax-free and penalty-free. It’s the only retirement account that doubles as a “Hey, I need money for a surprise emergency llama” fund. Playful exaggeration? Maybe. But it’s true. Roth IRAs are the superheroes of the financial world—they don’t wear capes, but they definitely wear tax-free armor.
The 401(k): The “Free Money From Your Boss” Trap
The 401(k) is the account your employer offers, often with a word like match attached. A match is when your company says, “Hey, if you put in 5% of your paycheck, we’ll throw in an extra 5% for free.” That’s not a joke—that’s literally free money. If you don’t take it, you are financially allergic to logic.
The downside? Your investment choices are usually limited to a menu of boring mutual funds that look like they were designed by a committee of accountants who hate fun. Also, there are contribution limits—around $23,000 in 2024 for most people, which is more than most of us have in our checking accounts. But if you leave your job, getting that money out can be a paperwork nightmare that makes filing your taxes feel like a vacation.
 Ngpf Compare Types Of Retirement Accounts
Pro tip from the NGPF answer key: the 401(k) match is the first financial goal you should hit. It’s literally free money. Ignore that, and you might as well throw your paycheck into a hole labeled “Regret.” After you hit the match, consider moving your extra savings to an IRA for better control. The 401(k) is like the gateway drug to retirement—it’s effective, but watch the side effects.
The Epic Showdown: Which One Wins?
Let’s do a quick cage match. Traditional IRA wins if you’re in a high tax bracket now and expect to be poorer in retirement. Roth IRA wins if you’re young, have low income today, and dream of tax-free yacht money. 401(k) wins if your boss is handing out free cash and you’re not a complete fool.
Surprising fact: you can have all three accounts at once. That’s right—you can triple-dip into the retirement punch bowl. It’s like ordering a burrito, tacos, and a quesadilla at the same restaurant. Is it extra work? Yes. But your future stomach (and bank account) will thank you.
The real answer key to retirement is simple: start today, avoid the urge to spend your savings on a jet ski, and use the NGPF resources to compare the options until your eyes cross. Or, you know, just print this article, tape it to your wall, and pray the math works out. Either way, you’re now one step closer to being that cool retiree who drinks margaritas at 10 a.m. and tells everyone, “I planned for this.” Enjoy your future beach hut.
