Is Pelvic Floor Reconstruction Covered By Insurance

So, you’re wondering if your insurance will actually pay for pelvic floor reconstruction. You’ve probably spent more time than you’d like discussing your bladder, uterus, or t...
So, you’re wondering if your insurance will actually pay for pelvic floor reconstruction. You’ve probably spent more time than you’d like discussing your bladder, uterus, or that mysterious “pressure down there” feeling. And now, you just want to know: will your wallet survive this, or will you have to sell a kidney on the black market? Let’s dive into the wonderful, wild world of insurance, minus the jargon that makes you want to nap.
The Short Answer (Spoiler Alert!)
Yes, pelvic floor reconstruction is typically covered by insurance. But—and there’s always a “but” with insurance, right?—it depends on why you need it.
Insurance loves a medical necessity. If your pelvic floor is staging a mutiny because of prolapse, incontinence, or chronic pain, you’re in good company. If you’re just doing it for a “tighter” feel (ahem, cosmetic reasons), your insurance will probably laugh and send you a bill for a consultation.
Must Read
Medical vs. Cosmetic: The Fine Line
Here’s the golden rule: If it hurts, leaks, or interferes with your quality of life, it’s medical. If it’s just about aesthetics? That’s cosmetic, and your insurance will say “not our problem.”
Think of it like this: fixing a hernia is covered; getting a tummy tuck for fun is not. Pelvic floor reconstruction is almost always in the “fixing a hernia” category. (But please, do not compare your uterus to a hernia at the doctor’s office—they might side-eye you.)
What Your Insurance Will Actually Ask For
Your insurance company (let’s call them “The Paperwork Gremlins”) will want a few things before they open their wallets. First, a diagnosis code. That’s a fancy number for “your pelvic floor is being dramatic.” Common diagnoses include cystocele (bladder falling into the vagina), rectocele (that’s the rear end making an unscheduled appearance), or stress urinary incontinence (when you sneeze and need a life jacket).
Second, they want proof. Your doctor needs to document that you’ve tried conservative treatments first. That means pelvic floor physical therapy, Kegels (the exercise that feels like trying to stop a sneeze mid-sneeze), or even a pessary (a little device that’s basically a support bra for your vagina).
If you’ve done all that and it still failed? Boom. Insurance is much more likely to say, “Fine, we’ll pay.”
The Pre-Authorization Dance
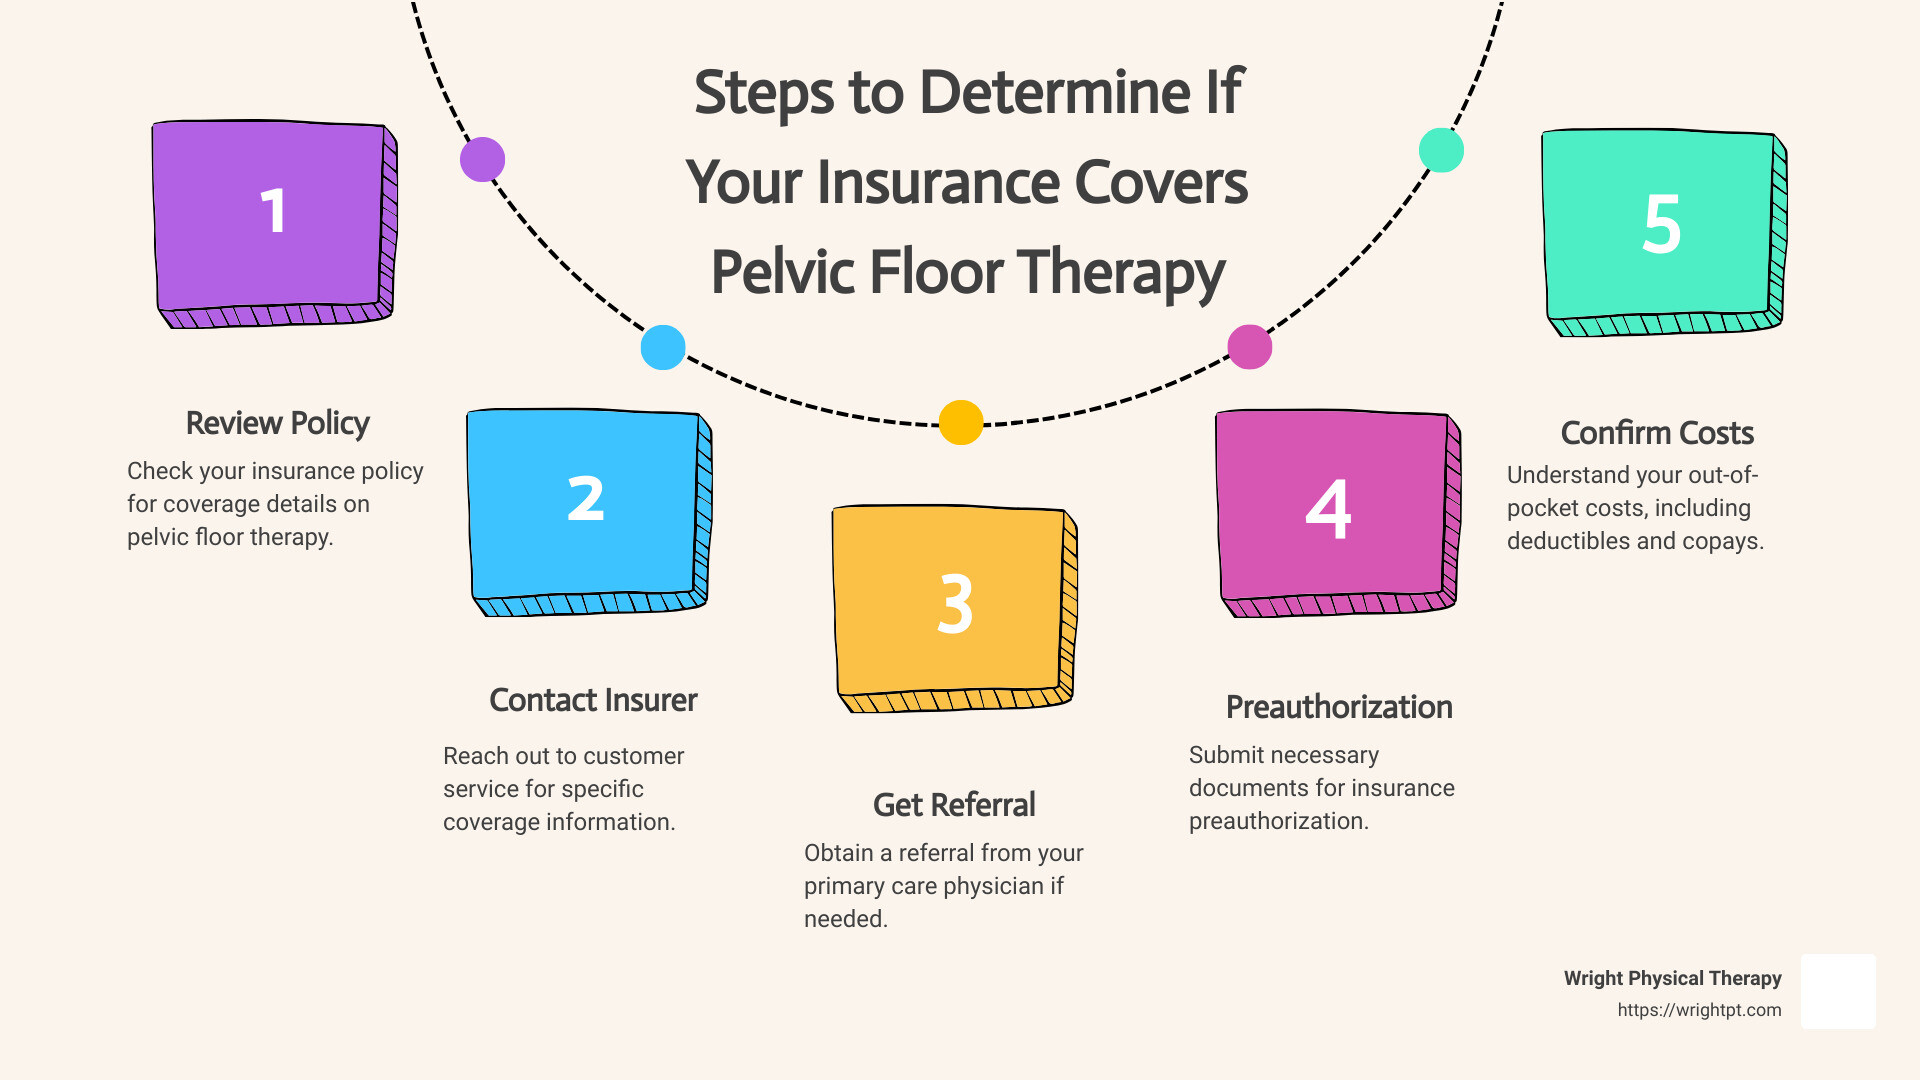
Before you schedule surgery, you’ll need pre-authorization. This is where your doctor’s office talks to your insurance company in a secret language involving forms and fax machines (yes, those still exist).
 How To Check Insurance For Pelvic Floor Therapy? - YouTube
Don’t skip this step. It’s like asking for permission before you use the last slice of pizza—if you don’t ask, you might get a really awkward surprise later. And that surprise usually comes in the form of a $20,000 bill.
What About the Actual Cost?
Even with insurance, you’ll probably still have to pay something. Deductibles, copays, and coinsurance are the three horsemen of the healthcare apocalypse. For example, if your deductible is $3,000, you’ll pay that first. Then insurance covers the rest (usually 80%, and you pay 20%).
But here’s a fun fact: pelvic floor reconstruction is often considered “medically necessary” and may qualify for “in-network” rates. That can save you thousands. Just make sure your surgeon and hospital are in-network, or you’ll be paying for their summer vacation.
Pro tip: Call your insurance before the surgery. Ask for the specific CPT codes for your procedure. Write them down. Tape them to your fridge. If the person on the phone sounds confused, ask for a supervisor. Be politely annoying—it’s your money.
What If They Say No?
If your insurance denies coverage, don’t panic. You can appeal. And appeals actually work more often than you think. Gather your medical records, a letter from your doctor explaining why this is vital (use words like “disabling” and “significantly impacts daily function”—insurance loves dramatic adjectives), and send it in.
Also, check if you have out-of-network benefits. Some plans cover surgery even if your doctor isn’t in their club. It might cost more, but it’s better than a total denial.
 How Can I Check Pelvic Floor Therapy Insurance Coverage? - YouTube
Medicare and Medicaid: Different Rules
If you’re on Medicare or Medicaid, the coverage rules are a bit different. Medicare typically covers pelvic floor reconstruction if it’s for prolapse or incontinence. Medicaid varies by state, so you might need to do some extra homework. (Spoiler: your state’s website probably has a link that says “pelvic floor coverage” buried under 47 submenus. Good luck!)
But hey, most public insurance plans recognize that a falling pelvic floor is a real health issue, not a luxury spa treatment.
Real Talk: The Emotional Side
I know this topic can feel embarrassing. You’re basically asking a stranger in a cubicle if they’ll pay to fix your “girlie bits.” But remember: your pelvic floor is a muscle, just like your hamstring or bicep. You wouldn’t feel weird asking insurance to fix a torn hamstring, right? (Well, maybe you would, but you shouldn’t.)
Own it. Say it loud: “I need pelvic floor reconstruction because my body is having a mechanical failure, and I deserve to pee without a trampoline.” Trust me, the insurance rep has heard way weirder things. (Like the time someone tried to claim a pet llama as a medical expense. True story.)
The Final Uplifting Conclusion
So, here’s the good news wrapped in a sparkly bow: Your insurance will likely cover pelvic floor reconstruction as long as it’s for health reasons, not vanity. You’ve got this. You’ll do the pre-auth dance, pay your deductible, and soon you’ll be sneezing, laughing, and jumping on a trampoline without a second thought.
And when you finally get that surgery done, don’t forget to thank your pelvic floor for its service. It’s been holding up the fort (literally) for years. It just needed a little vacation—and a good repair crew. You are so worth it. Now go call your insurance, and maybe reward yourself with a cupcake after. You’ve earned it. 💪🍰
