How To Solve Bank Reconciliation Statement Problems

So, you’ve got a bank reconciliation statement staring back at you, and it feels like a pop quiz you didn’t study for. Don’t worry—I’ve been there, and I promise it’s not as s...
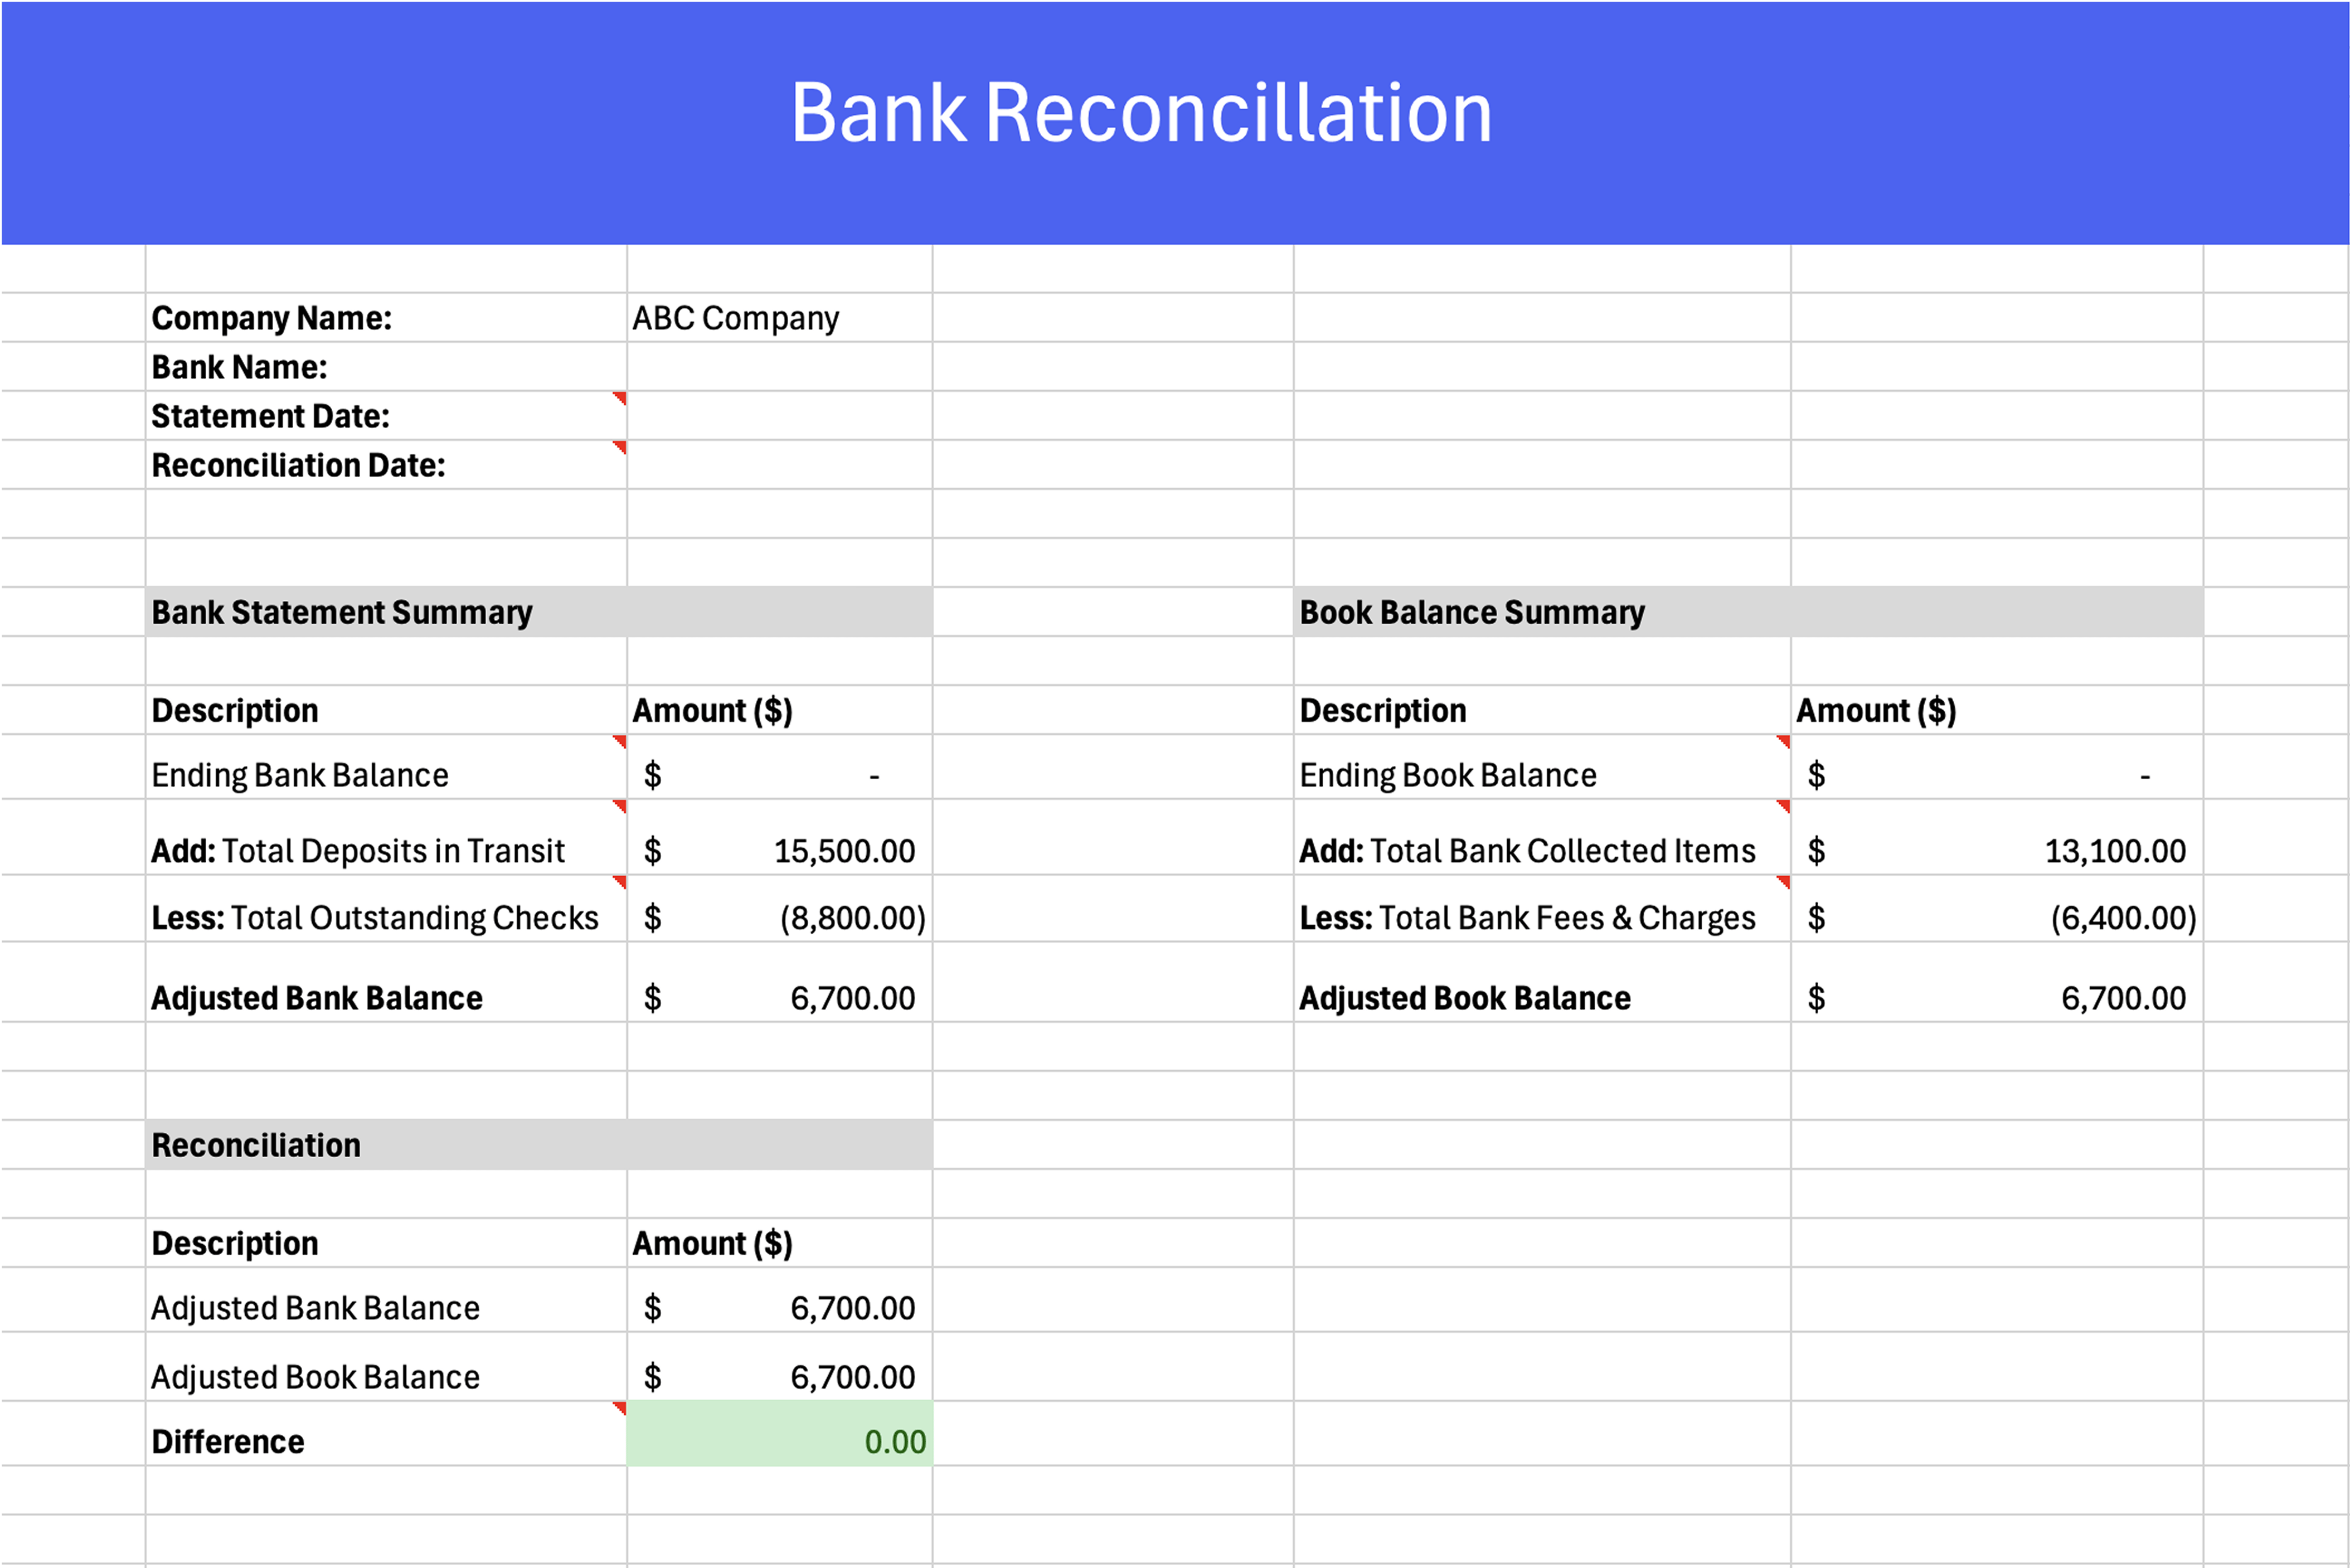
So, you’ve got a bank reconciliation statement staring back at you, and it feels like a pop quiz you didn’t study for. Don’t worry—I’ve been there, and I promise it’s not as scary as it looks. Think of it as a detective game where you’re matching up two slightly messy lists of transactions. Ready to crack the case? Let’s do this.
Step 1: Gather Your Clues
First, grab your company’s cash book (your internal record) and the bank statement from your friendly neighborhood bank. These are your two star witnesses, and they might not agree on everything. Did you know that banks sometimes charge fees before you even notice? Sneaky, right?
Lay them side-by-side on your desk—or better yet, open two browser tabs if you’re digital. The goal here is to find where they dance in sync and where they trip over each other. Start with the opening balances; if they match, you’re already winning.
Must Read
Step 2: Stamp Out the Easy Matches
Go through each transaction and mark off the ones that appear on both records. This is the “low-hanging fruit” part, and it feels like crossing items off a grocery list. Use a highlighter or a checkmark—whatever makes you feel like a pro.
For example, if you see a deposit of $500 on both sides, bam—match made in heaven. Ignore it for now and move on to the suspects that don’t line up. Those mismatches are where the mystery lives.
Pro Tip: Don’t Rush This Part
I once missed a match because I was daydreaming about pizza. Double-check every single entry, especially near month-end when things get wild. A tiny typo can throw off your entire balance—like a rogue cat on a keyboard.
Step 3: Hunt Down the Usual Suspects
Now, look for the classic troublemakers: outstanding checks and deposits in transit. An outstanding check is one you wrote but the bank hasn’t cashed yet—kind of like sending a friend an IOU they forgot to redeem. Deposits in transit are cash or checks you’ve banked but the bank hasn’t processed by the statement date.
List these separately on your worksheet. Don’t panic—they’re not errors, just timing differences. Think of them as your train arriving late while the station clock says it’s already there.
Step 4: Banks Make Mistakes Too (Gasp!)
Banks are not infallible—shocking, I know. Sometimes they charge a fee you didn’t authorize, or they accidentally credit your account twice. Check for bank errors like a hawk. If you find one, call your bank and say, “Hey, buddy, fix this.”
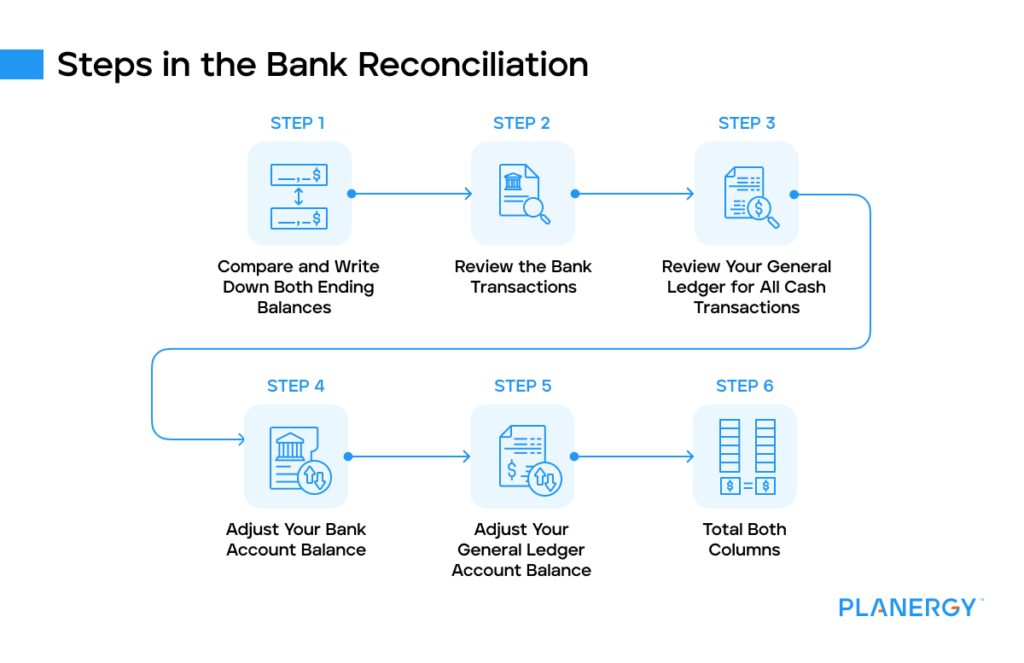 Bank Reconciliation: What It Is & Best Practices : PLANERGY Software
Also, look for interest income or NSF fees (non-sufficient funds fees) that you haven’t recorded yet. Your cash book might be blissfully unaware of these little gremlins. Add or subtract them in your book to match the bank’s version of the truth.
Side Note: NSF Fees Are the Worst
If a customer’s check bounces, it’s like getting an “invitation” to a party you didn’t want to host. Just record the fee and politely remind Mr. Customer to pay up.
Step 5: Adjust Your Cash Book
Now, this is where the magic happens. Update your company’s cash book for any items the bank recorded that you missed—like those sneaky bank charges or direct debits. Do not change the bank statement; that’s the bank’s job.
Instead, adjust your book balance until it agrees with the bank’s adjusted balance. Write it down clearly: “Add: Interest income,” “Less: Bank service charge.” It’s like giving your cash book a little haircut and a shave.
Step 6: The Grand Finale—Reconciliation
Take a deep breath. Now, create your reconciliation statement format. Start with the bank statement balance, then add deposits in transit and subtract outstanding checks. That gives you the adjusted bank balance.
Next, take your cash book balance, and add or subtract the items you adjusted earlier (bank errors, fees, interest). Compare the two adjusted balances—if they match, you’ve cracked it! High-five yourself or do a little victory dance. (I do the “accountant shuffle.” It’s not pretty, but it works.)
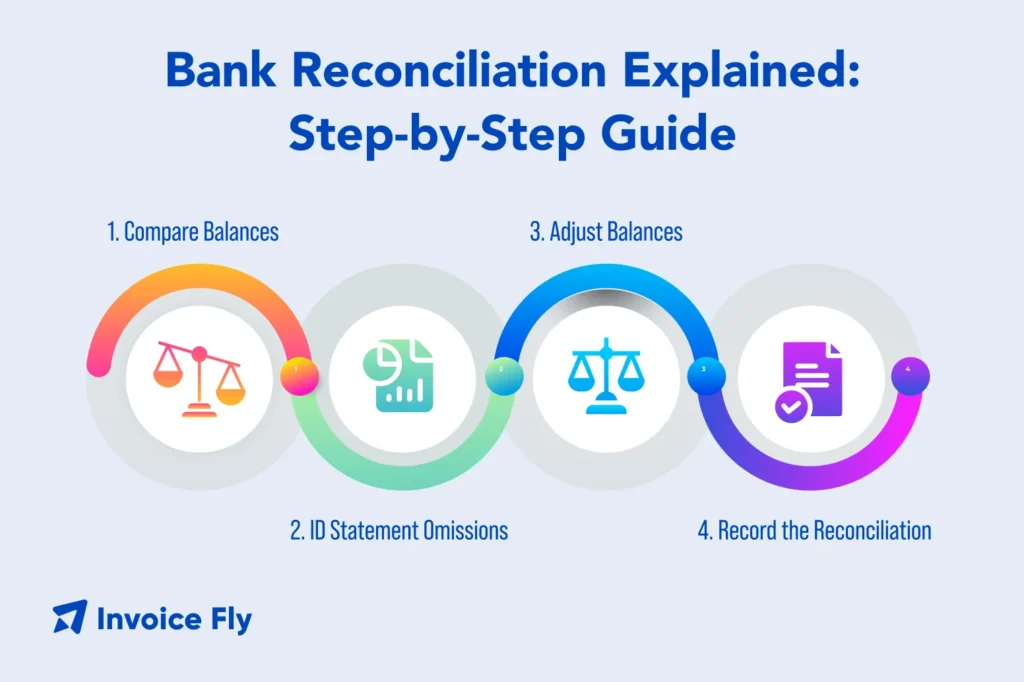 Bank Reconciliation: How It Works in 6 Steps (with Examples) – Invoice Fly
If they don’t match? Don’t scream. Recheck your math, look for missing transactions, and remember: the numbers are never out to get you. They’re just shy about telling the truth.
Why This Matters (Besides Not Crying)
Reconciliation isn’t just busywork—it’s like flossing for your finances. It catches errors, prevents overdrafts, and keeps your business healthy. Plus, your auditors will adore you. True story: a well-done bank rec has saved me from a panic attack three times.
And here’s the secret: once you’ve done it a few times, it becomes almost… fun. Okay, maybe not fun, but definitely satisfying. Like finishing a jigsaw puzzle where all the pieces were in the same room.
You’ve Got This!
So next time your bank statement lands in your inbox, don’t hide under your desk. You’re now armed with the sacred knowledge of outstanding checks and bank errors. You are a reconciliation ninja.
And remember: even the best accountants mess up sometimes. I once reconciled a statement to find out the bank had recorded my cat’s name as a transaction—I’m not kidding. The point is, you learn, you laugh, and you balance the books. Go forth and reconcile with joy!
🌻 Now go treat yourself to a cookie. You earned it.
