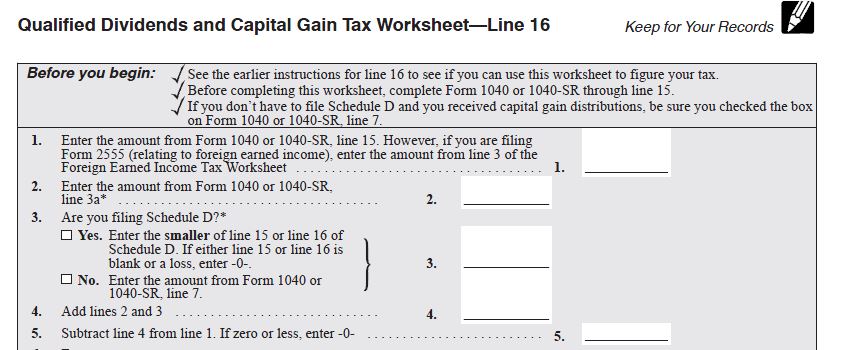
Qualified Dividends And Capital Gain Tax Worksheet Line 16

Let’s be honest: tax forms are the uninvited guests at the annual party of your financial life. They show up with a clipboard, demand explanations, and refuse to leave until y...

Let’s be honest: tax forms are the uninvited guests at the annual party of your financial life. They show up with a clipboard, demand explanations, and refuse to leave until you’ve confessed every dollar you earned. But every year, you reach a moment of clarity, usually after three cups of coffee and a muttered swear word, when you stumble upon Line 16 of the Qualified Dividends and Capital Gain Tax Worksheet.
You’d think the IRS labeled it “Line 16” just to make you feel like you’re getting a secret handshake. In reality, it’s the spot where you figure out how much of your investment wins get to slide on a lower tax rate. It’s like a VIP section at a concert, except the bouncer is a tax accountant with a calculator.
What Exactly Is This Mystical Line?
Imagine you bought a stock, held it long enough to get bored, and then sold it for a profit. That’s a capital gain. Or maybe a company paid you a nice little check for owning their shares—that’s a qualified dividend. Line 16 is where you tell the IRS, “Hey, I played the long game, so please don’t take a huge bite out of my sandwich.”
Must Read
If you’re like my neighbor Bob, who sold some Apple shares to buy a new grill, this line is your best friend. Bob once filed his taxes without looking at Line 16 and ended up paying the same rate as his salary. He still talks about it like a war story: “I could have bought a second grill with the difference!”
The Math (Don’t Panic)
The worksheet itself looks like a game of hopscotch designed by a sadist. You start with your total taxable income, then subtract some stuff, add some stuff, and finally—poof—you land on Line 16. The number there tells you how much of your gains get the preferential tax rate, which is fancy IRS-speak for “less pain.”
Think of it this way: ordinary income is taxed like a speeding ticket from a state trooper—painful and unavoidable. Qualified dividends and long-term capital gains are more like a parking ticket in a sleepy town: you still pay, but it’s barely a nuisance. Line 16 is the map that shows you the sleepy town route.
I once watched a friend, let’s call her Sarah, spend four hours on this worksheet. She kept getting confused and yelling at her laptop. “Line 16 is the Bermuda Triangle of my living room!” she shouted. Eventually, she realized she had misread the instructions and her total was actually lower. She celebrated by buying a bagel.
 IRS Schedule D Walkthrough (Capital Gains and Losses) - Worksheets Library
Why Should You Care?
Because the difference between ordinary income tax and the capital gains rate can be huge. For a single filer, the 0% capital gains rate can apply if your income is under a certain threshold. Yes, zero percent. That’s like finding a $20 bill on the sidewalk and not having to pay taxes on it. It’s illegal not to!
If you’re in the 15% capital gains bracket, you’re still doing better than if you had earned that same money from a side gig. Your side gig pays self-employment tax, Social Security, and Medicare. Your stock sale? Just the capital gain. It’s like the IRS gives you a high-five for being patient.
And here’s the kicker: most people accidentally overpay because they skip Line 16. They look at the standard tax tables, see a big number, pay it, and move on. But if you have qualified dividends, you’re legally owed a lower rate. It’s like paying full price for movie popcorn when you have a coupon in your pocket.
The “Aha!” Moment
I remember my own first encounter with Line 16. My investment account had a tiny dividend—like, enough for a fancy coffee. I assumed I’d pay my normal rate. But when I filled out the worksheet, my tax dropped by a few hundred dollars. I literally leaned back in my chair, smiled, and whispered, “Thank you, John Maynard Keynes.”
 VTIAX Foreign Source Income for Foreign Tax Credit - Bogleheads.org
Now, does that mean you should ignore Line 16 if you only made $50 from dividends? Absolutely not. Every dollar you save is a dollar you can spend on something ridiculous, like a novelty T-shirt or a third cup of coffee. Plus, the IRS expects you to use the worksheet if you have qualified dividends. Ignoring it is like showing up to a potluck with nothing but a fork—technically allowed, but deeply unhelpful.
The Golden Rule
Here’s the easy-going takeaway: Don’t be a hero. You don’t need to memorize the tax code. All you need to remember is that Line 16 is your friend. It’s the quiet helper that whispers, “You held that stock for more than a year. You earned a lower rate. Take a victory lap.”
If you’re using tax software, it usually fills this out automatically. But check it! I once had a software glitch that treated my dividends like lottery winnings. I had to manually override it using Line 16. The fix took three minutes and saved me the cost of a nice dinner.
And if you’re still confused, imagine you’re teaching this to your grandma. “Grandma, Line 16 is where the government says ‘thanks for not day-trading like a maniac.’” She’ll nod, pat your hand, and then ask if you’ve eaten enough. But the point sticks.
So next time you see that worksheet, don’t sigh. Grab a snack, put on some music, and give Line 16 the respect it deserves. It’s the least exciting hero of tax season, but it’s also the one that hands you back your own money. And honestly? That’s the kind of magic we all need.
