Cost Segregation Study Residential Rental Property Example

Okay, grab your coffee and pull up a chair. Let’s talk about something that sounds incredibly boring but is actually a secret money hack for landlords. I’m talking about a cos...
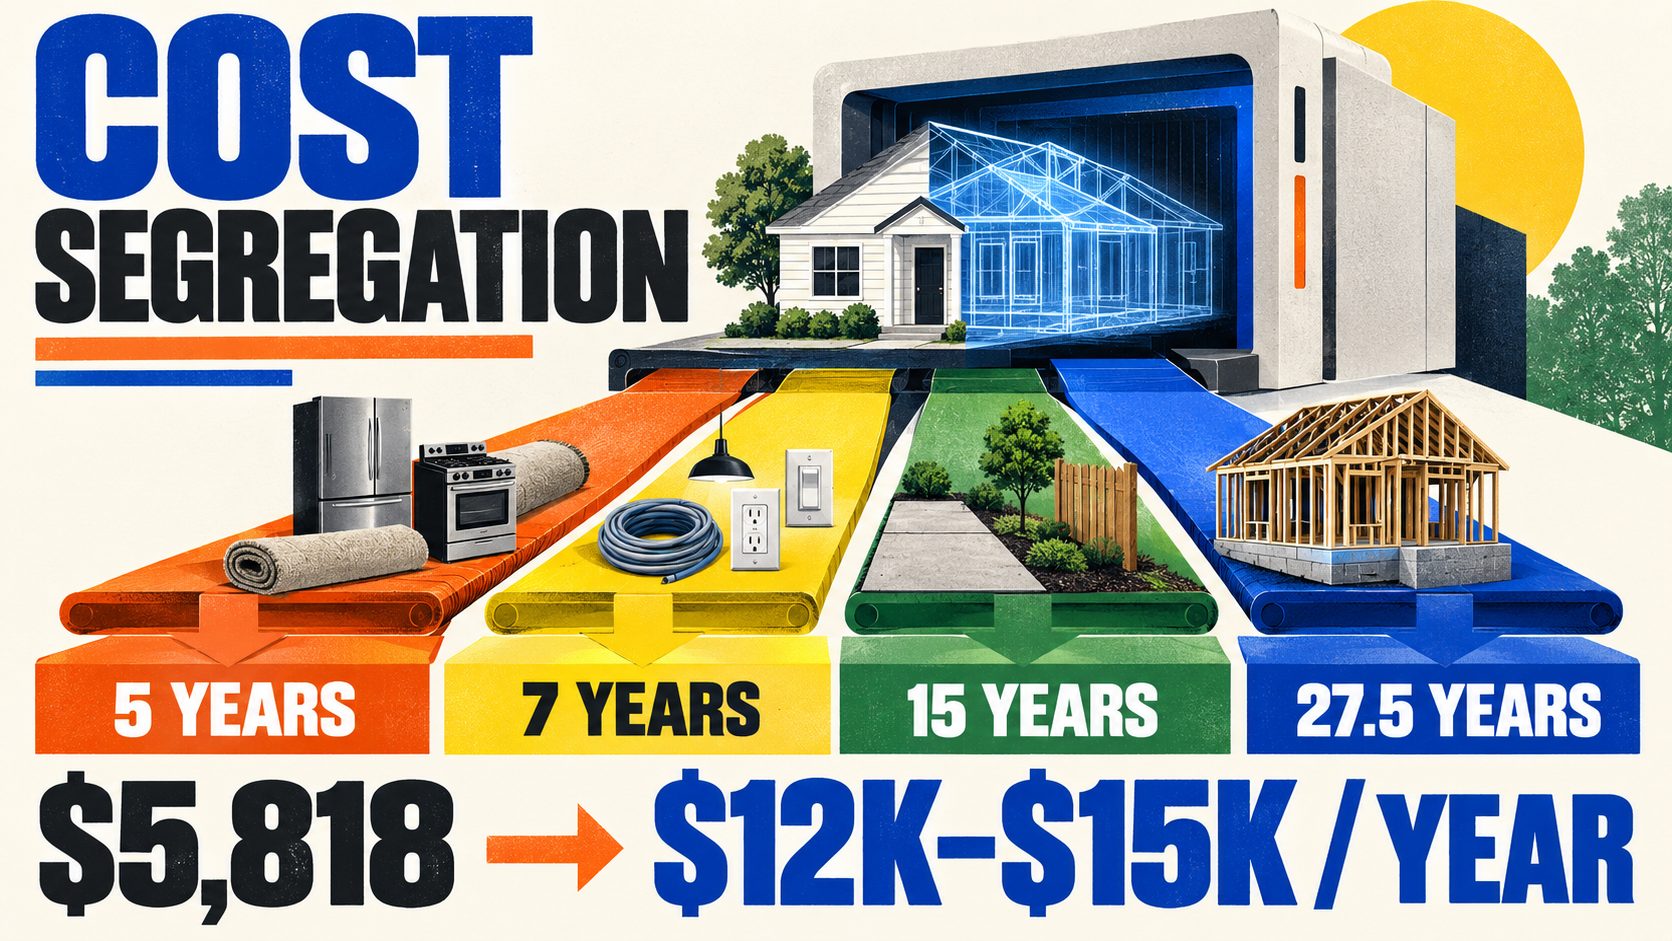
Okay, grab your coffee and pull up a chair. Let’s talk about something that sounds incredibly boring but is actually a secret money hack for landlords. I’m talking about a cost segregation study.
I know, I know. Your eyes just glazed over. But stick with me—this is like finding a twenty-dollar bill in an old jacket, except it’s more like finding thousands of dollars.
What Even Is a Cost Seg Study?
Imagine you buy a rental property for $500,000. Normally, you’d depreciate that whole building over 27.5 years. That’s the slow boat to tax savings.
Must Read
A cost segregation study is a fancy engineering report that says, “Hey, not all of that is the building.” It breaks out the stuff that wears out faster—like carpets, cabinets, and parking lots.
That stuff is called personal property and land improvements. And you can depreciate them in 5, 7, or 15 years instead of waiting nearly three decades. Boom. Bigger deductions now.
A Real-Life Example (Because Examples Are Fun)
Let’s say you buy a fourplex for $800,000. The land is worth $200,000 (land doesn’t depreciate, sorry). So your building cost is $600,000.
Normal depreciation gives you about $21,818 a year for 27.5 years. Not bad, right? But a cost seg study might reclassify 25% of that $600k into shorter-life assets.
That’s $150,000 worth of stuff like flooring, window AC units, and light fixtures. You can now depreciate that chunk in just 5 years. Your first-year deduction could jump to over $50,000. Yes, please.
You just turned a tax bill into a refund. Who doesn’t love that?
Is This Legal? (Spoiler: Yes)
This isn’t some loophole your shady uncle invented. The IRS actually encourages this. There’s even a specific section in the tax code for it (Revenue Procedure 87-56, if you’re a nerd like me).
 Cost Segregation Study: How Bonus Depreciation Works - Crushing REI
You hire a specialized engineering firm. They crawl through your property (or look at plans) and identify every single component. Then they slap a depreciation schedule on it.
It costs about $2,000 to $5,000 for a study. But on an $800k property? The tax savings in the first year alone often cover that cost. And then some. It’s a no-brainer if you plan to hold the property for more than a couple of years.
Wait, There Are Rules?
Of course there are. This is real life, not a magic wand. You need to have a constructed, purchased, or renovated property. Bonus depreciation (which lets you take a huge chunk upfront) is also in play.
Right now, bonus depreciation is at 80% for 2023. But it’s phasing down. So if you’ve got a property, do this sooner rather than later. Don’t wait until the coffee gets cold.
Also, this works best for properties worth at least $500,000. If you’ve got a tiny duplex worth $200k, the study might cost more than the benefit. Use common sense, friend.
The Fun Part: Running the Numbers
Let’s revisit our fourplex example. Without the study: $21,818 deduction in year one. With the study: Approximately $58,000 deduction in year one.
That extra $36,000ish deduction saves you about $10,000 to $14,000 in taxes (depending on your bracket). That’s a new roof. Or a really nice vacation. Or more rentals.
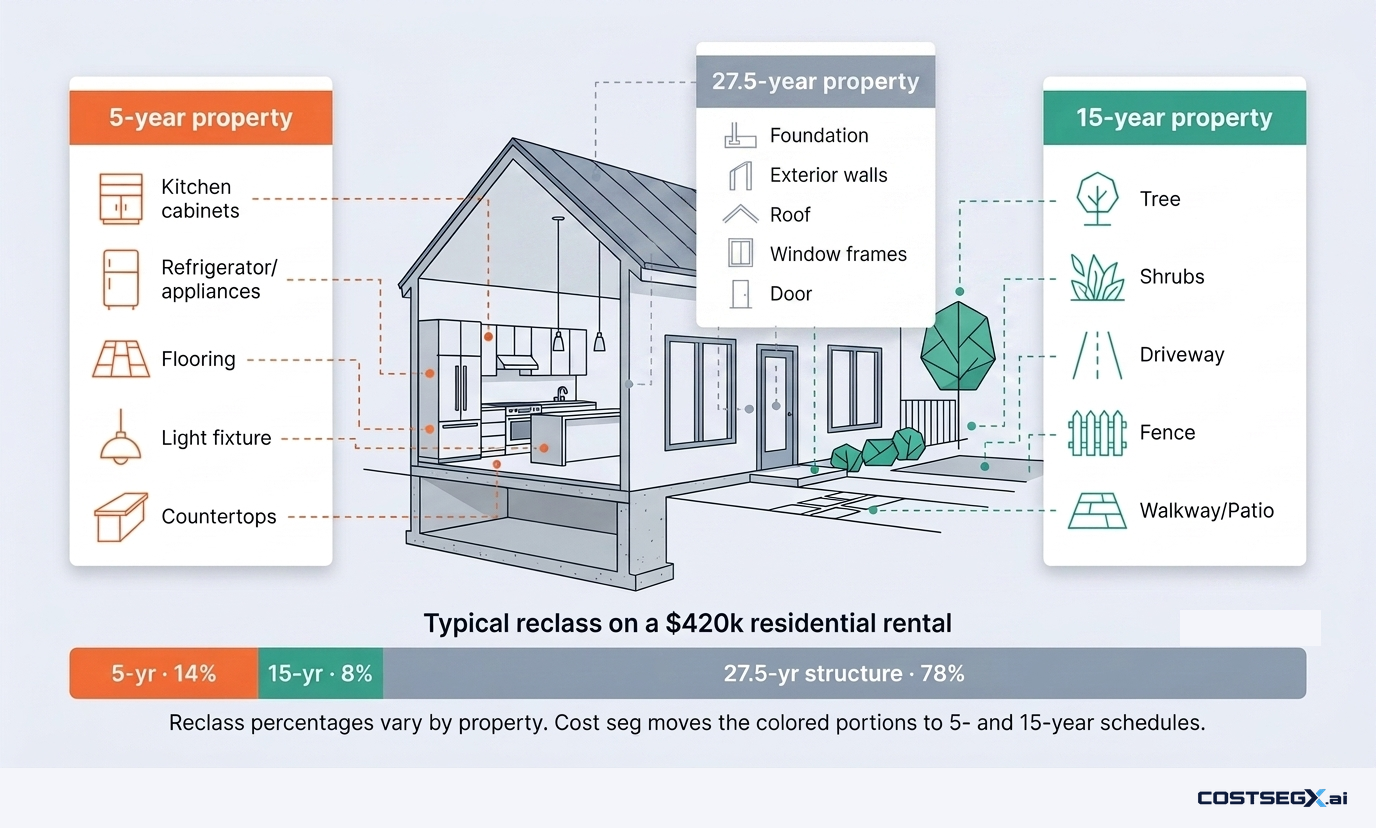 AI-Powered Cost Segregation for Rental Properties | CostSegX
And guess what? Over five years, you’ll have deducted way more than you would have. The tax deferral is massive. It’s like giving the IRS an IOU instead of cash. Chef’s kiss.
But Wait, There’s a Catch (Isn’t There Always?)
Yes. When you sell the property, you’ll have to recapture some of that depreciation. That’s the IRS saying, “Thanks for the loan—now pay us back.”
But here’s the thing: You’ll probably do a 1031 exchange when you sell. That defers the recapture taxes entirely. Or you might hold the property until you die, and your heirs get a step-up in basis. Boom—taxes wiped out.
So the catch is more of a gentle reminder to plan ahead. Not exactly a crisis.
Should You Do It?
If you own rental property and you’re not doing a cost seg study, ask yourself: Why are you leaving money on the table? Is it because it sounds complicated? Hire someone. It’s their job to make it simple.
Is it because you didn’t know? Well, now you do. So no more excuses.
Grab a coffee, call a tax pro who specializes in real estate, and ask them about a cost segregation study. Your future self—with a fatter wallet—will thank you.
Now go forth and depreciate faster. You’ve got this.
