Equals How Much Is Owned Minus How Much Is Owed

The phrase sounds simple enough: what you own minus what you owe. That single equation is the foundation of your net worth — a number that quietly shapes nearly every financia...
The phrase sounds simple enough: what you own minus what you owe. That single equation is the foundation of your net worth — a number that quietly shapes nearly every financial decision you make. Yet most of us never sit down and actually calculate it.
The Equation Behind Your Wealth
Imagine all the physical and financial assets you possess stacked on one side of a scale. Then place every dollar you owe — mortgages, car loans, credit cards — on the other side. When the dust settles, one number remains: your net worth.
This formula isn't reserved for millionaires in boardrooms. It applies to a college student with $500 in savings and $2,000 in student debt just as naturally as it applies to a retiree with a paid-off home. The mechanics are universal, and the script role is in seeing where you currently stand.
Must Read
Fun little fact: the concept of net worth dates back to medieval European accounting, where merchants tracked their business standing on scrolls — with pen and ink, no less. Today, you can punch the numbers into a phone app before your coffee finishes brewing.
Assets: The "Owns" Side
Assets go far beyond your bank balance. They include real estate, investments, vehicles, jewelry, art, and even that vintage guitar gathering dust in the closet. Every tangible or financial thing that could be sold or converted into cash counts.
Many people underestimate intangible assets too. A small business, intellectual property, or a loyal freelance client base can all carry measurable value. If it has a price tag or earning potential, it belongs on this side of the equation.
Think about how social media influencers treat their followings — their audience is essentially an asset that generates income. The same logic applies to a reputation for reliability in your career.
 How Much Does Us Owe Money
Liabilities: The "Owes" Side
Liabilities are the commitments keeping your future paycheck on a leash. Credit card balances, student loans, mortgage payments, and car financing all live here. The smaller this number, the lighter your financial breathing room.
The tricky thing is that not all debt feels equally oppressive. A mortgage at a low interest rate might build equity over time, while a 28% credit card balance quietly drains you monthly. Distinguishing productive debt from destructive debt is a crucial step.
Cultural reminder: in Japanese culture there's a saying — "Debt eats the heart before it eats the wallet." Emotional awareness around owing money matters just as much as mathematics.
Why Your Net Worth Matters
Net worth is the true pulse check of your financial health — not your salary alone. A person earning $150,000 a year but carrying $400,000 in debt has a deeper hole than someone earning $60,000 with zero obligations. Income is temporary; net worth is lasting.
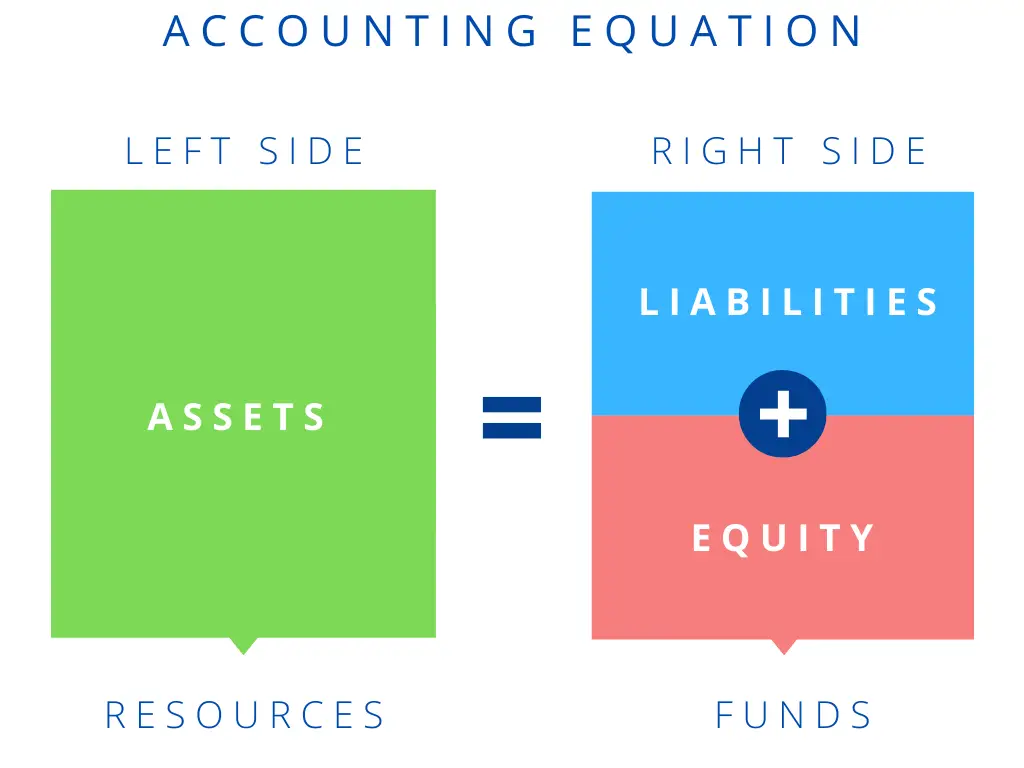 Why Must Accounting Equation Always Balance | Accountingo
Track it annually or even quarterly. Watching that number climb — or catch a slide early — turns abstract money into something you can actually feel and steer. Progress, even small, fuels motivation more than any budgeting lecture ever will.
Practical Tips to Grow the Gap
Start by automating savings the moment your paycheck lands. Even tiny automatic transfers to an emergency fund compound into serious breathing room over time. Future you will thank past you for every dollar you didn't spend impulsively.
Tackle high-interest debt aggressively while preserving low-interest mortgage debt if it builds equity. A practical strategy: use the avalanche method, paying off the highest interest rate first to save the most money. The psychological win of eliminating a balance also keeps momentum alive.
Invest early and stay boring with it. Consistent index fund contributions over decades have historically outperformed most individual stock-picking attempts. Time in the market beats timing the market — a phrase that sounds cliché precisely because it keeps proving itself true.
 Definition, Explanation and Examples – Glass design
Don't overlook free wealth-building habits either. Negotiating your salary once every two years or cutting one unnecessary subscription adds up quietly but meaningfully. Small lifestyle tweaks are the unsung heroes of net worth growth.
A Little Perspective
In the 2008 financial crisis, households with positive net worth weathered the storm far better than those swimming in negative territory. It wasn't about having enormous wealth — it was about the buffer between what was owned and what was owed. Safety is more valuable than luxury in uncertain times.
Conversely, jump fifty years forward and today's tech billionaires show the upside of asset-heavy, debt-light portfolios. The equation never changed — owns minus owes — only the numbers got imaginatively larger. It's the same rule that governed hand-kept ledgers centuries ago.
Reflection: What This Really Means for Daily Life
Every latte you skip, every loan you chip away at, every time you choose saving over showing off — you are writing on both sides of that equation. Net worth is not a number; it's a daily conversation your choices keep having.
The goal isn't overnight transformation or becoming a character in a lifestyle ad. It's simply knowing your position clearly so you can move forward with calm confidence. And in a world that loves comparing highlight reels, a quiet, growing net worth is maybe the most honest measure of where you truly are.
