What Is A Principal Balance On A Car Loan

Ever glanced at your car loan statement and thought, "Wait, what's this principal balance thing?" You're not alone. Let's break it down in the easiest way possible, because ho...
Ever glanced at your car loan statement and thought, "Wait, what's this principal balance thing?" You're not alone. Let's break it down in the easiest way possible, because honestly, money stuff doesn't have to feel boring.
So, What's the Principal Balance?
The principal balance is simply the amount of money you still owe on your car before any interest is added. Think of it like the skeleton of your loan — the original cost minus whatever you've already paid down.
If you borrowed $20,000 for a used Honda and you've knocked off $5,000 so far, your principal balance is $15,000. That's it. Nothing fancy, nothing scary.
Must Read
Wait, Isn't That Different From What I Actually Pay?
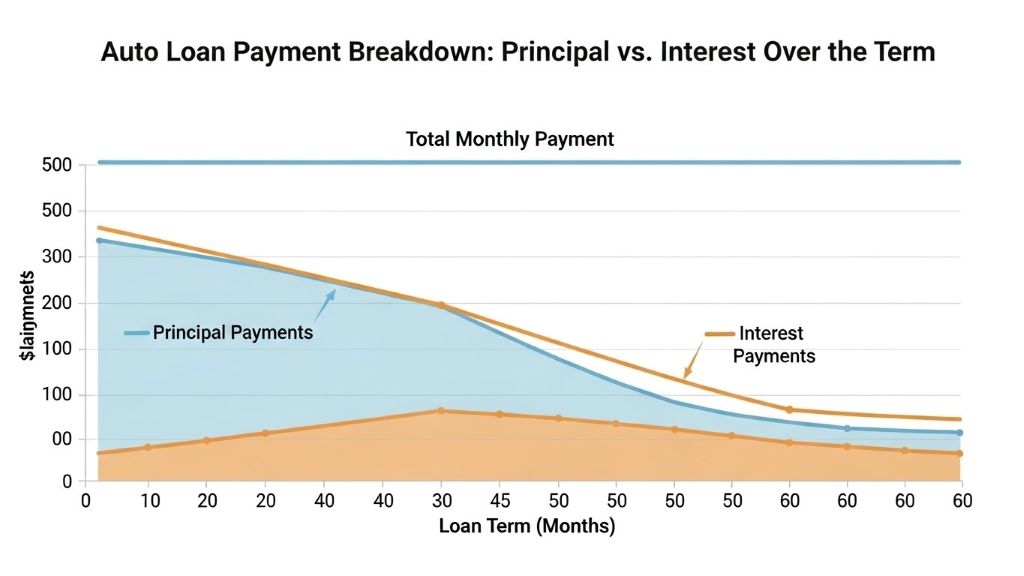
Absolutely, and this is where it gets interesting. Each monthly payment you make actually splits into two parts — one chunk goes toward your principal balance, and the other covers the interest the lender charges you.
It's kind of like eating a pizza where one slice is what you actually ordered, and the other is the delivery fee you didn't ask for. Nobody loves the delivery fee, but you can't skip it.
Why Should You Even Care About Your Principal Balance?
Because tracking it is like watching your progress meter fill up in a video game. Every dollar you shave off the principal means you owe less over time, which means less interest in the long run.
More money toward the principal early on can save you a surprising amount of cash. It's one of those quietly powerful money moves that feels super satisfying.
 Financing Principal And Interest
Imagine your loan as a mountain you're climbing. The principal balance is how far you still have to go — and every payment is one step higher.
The Interest Sneak Attack
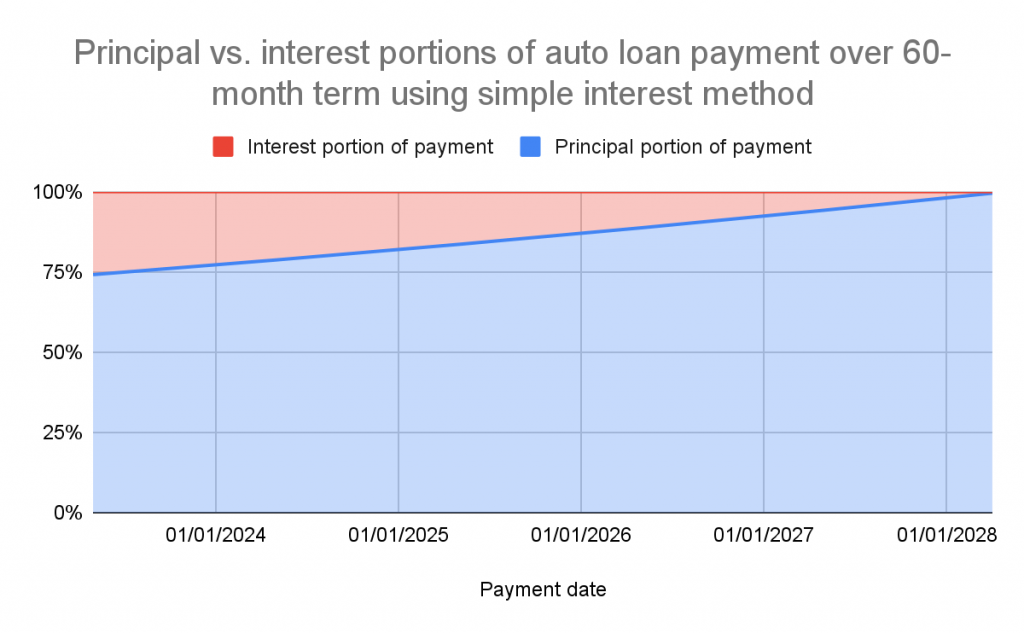
Here's the tricky part most people miss. In the early months of your loan, a larger slice of your payment goes toward interest rather than the actual balance.
So if you've been paying for six months and your principal barely moved — don't panic. That's totally normal, and it's just how the math works at first.
Over time, though, the balance starts shrinking faster, and more of your payment chips away at what you originally owed. It's like a snowball rolling downhill — slow at first, then gaining speed.
 How Do Auto Loans Work? | LendEDU
Easy Trick: Check Your Statement
Your monthly loan statement usually shows the principal balance right up front. Look for it next to terms like "outstanding balance" or "remaining principal."
Keep an eye on it every few months. You'll get a little rush watching that number drop — trust me, it's oddly addictive.
Some people even like to print it out and tape it to the fridge as a motivation reminder. Hey, whatever works!
What Happens When It Hits Zero?
When your principal balance reaches zero, your car is officially fully paid off. No more monthly payments, no more lender emails, complete freedom.
 What is Principal in Finance in Auto Loans and Car Financing - Local
That moment feels like a small celebration. You basically go from "I owe a bank for my ride" to "this thing is all mine."
It's a surprisingly emotional milestone, even though it's just a number hitting zero. Some people literally honk their horn in the driveway.
Quick Recap
To sum it all up — your principal balance is the real debt sitting between you and owning your car outright. It's the number that matters most, and it gives you a clear picture of where you stand.
Don't overthink it. Just peek at it now and then, pay attention to how it changes, and enjoy the progress.
Car loans don't have to be confusing. Once you understand the principal balance, everything else falls into place rather nicely.
