How To Calculate Pension Monthly Payment

So, you're about to retire — or maybe you're already wrangling with the pension paperwork and your coffee is growing cold. Figuring out your monthly pension payment doesn't ha...

So, you're about to retire — or maybe you're already wrangling with the pension paperwork and your coffee is growing cold. Figuring out your monthly pension payment doesn't have to feel like solving a riddle written by a villain. Let's break it down together, nice and easy, like peeling a banana.
First Things First: What Even Is a Pension?
A pension is basically your employer (or the government) saying, "Hey, thanks for all those hard-working years — here's some regular income to help you enjoy retirement." It's the financial high-five you've earned after decades of showing up and doing the thing. Think of it as a monthly thank-you note — except it comes with actual money attached.
Pensions come in a few flavors: defined benefit, defined contribution, and sometimes a delicious combination of both. The one most people think about when they hear "pension" is the defined benefit plan, where your payout is calculated based on a specific formula. That's the one we're going to crack wide open today.
Must Read
The Golden Formula (It's Not As Scary As It Sounds)
Most pension plans use a formula that looks something like this: Final Salary × Years of Service × Accrual Rate. Yep, it's just three numbers multiplied together — no rocket science degree required. If you can use a calculator, you can figure this out.
Factor #1: Your Final Salary
Your final average salary is usually the average of your earnings over the last few years before retirement — often three to five years. Some plans use the highest single year, and some even throw in a bonus for overtime. It's like the pension universe decided to be a little extra generous for those of us who stayed late.
Factor #2: Years of Service
This is simply the total number of years you worked at the company. If you started at 25 and retired at 60, that's 35 years — nice round number, and bonus points if you actually enjoyed the job. The longer you worked, the bigger this number gets, which means more money in your pocket later. Loyalty actually pays off here!
 How to Compute SSS Pension
Factor #3: The Accrual Rate
The accrual rate (sometimes called the accrual percentage) is the rate at which you build up pension benefits each year. It might be 1.5%, 2%, or even 2.5% depending on your plan. Think of it as the speedometer of your pension — the higher the rate, the faster you're cruising toward a comfortable retirement.
Let's Crunch Some Numbers With a Real Example
Alright, ready for a fun little scenario? Let's say your final average salary is $60,000, your company's accrual rate is 2%, and you worked for 30 years. Plug that into the formula: $60,000 × 0.02 × 30 = $36,000 per year. Now we're talking!
To get the monthly payment, just divide that annual amount by twelve. So $36,000 ÷ 12 = $3,000 per month. Not bad for a little math you can do on a napkin.
Don't Forget: Not All Pensions Are Paid Out the Same Way
Some pensions offer a single-life payout, which means payments stop when you do — sorry, death has no sense of humor. Others offer a joint-and-survivor option, where your spouse keeps getting paid after you're gone. That's basically pension insurance for your partner, and honestly, it's a pretty sweet move.
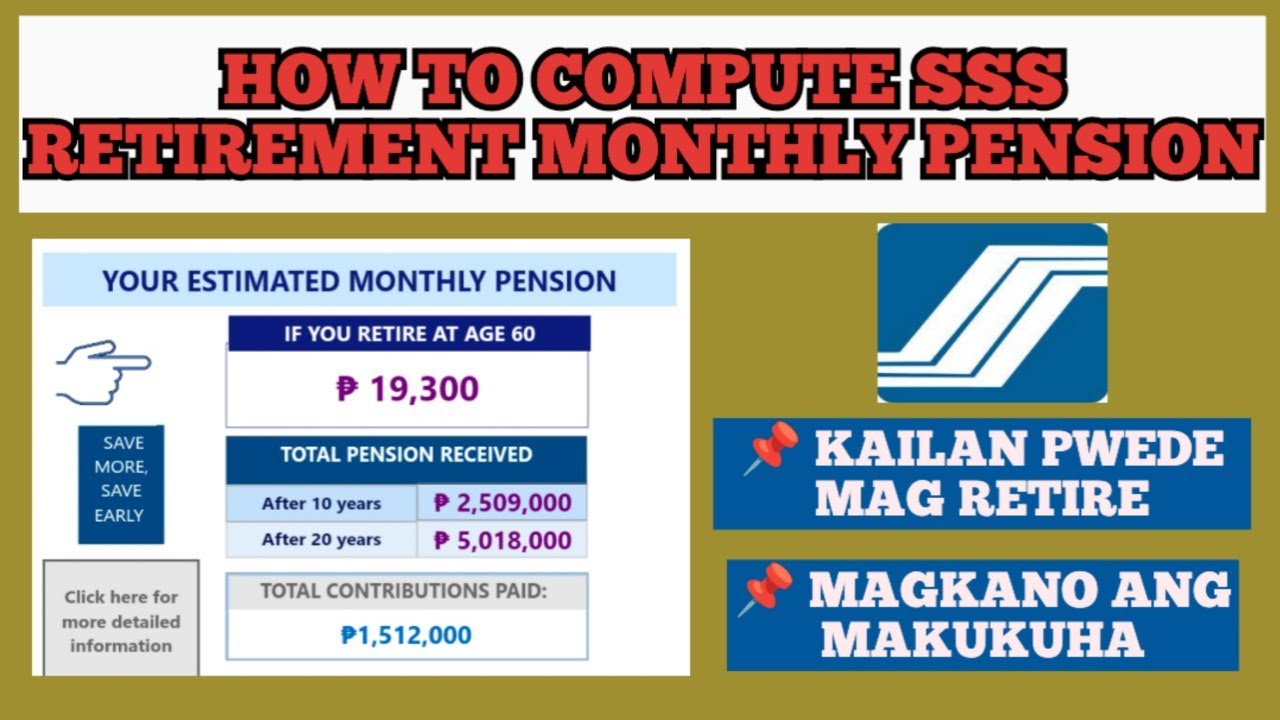 HOW TO COMPUTE SSS RETIREMENT PENSION MONTHLY | PAANO MA COMPUTE ANG
Choosing between these options changes how much you receive each month. The joint-and-survivor option usually gives you slightly less monthly but protects your better half. When in doubt, talk to your benefits department — they've heard every question already.
Adjustments That Can Change the Game
Some pension plans include cost-of-living adjustments (COLA), which bump up your payments each year to keep pace with inflation. Without COLA, your pension might feel like it's slowly shrinking — like a sweater that's been through too many hot washes. Always ask if your plan has this feature because it makes a huge difference over time.
You might also see early retirement penalties, typically about 5% reduction per year if you retire before the standard age. Basically, leaving the party early means you don't get to take home as much cake. Plan accordingly, my friend.
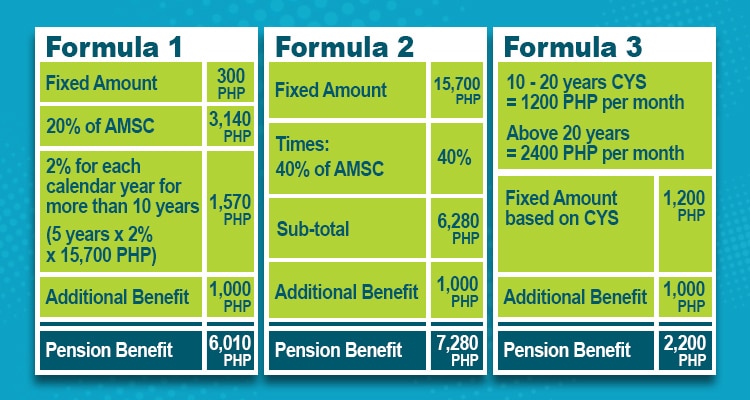 Ultimate Guide: Comprehensive List of Benefits you can get from SSS as
Quick Tips Before You Start Calculating
Check your plan documents carefully — every company does things a little differently, and assumptions are the mother of all mistakes. Use an online pension calculator if you want a quick sanity check, but always confirm with your HR team. And remember, rounding errors are no joke when thousands of dollars are involved.
Also, don't forget to factor in taxes. Your gross pension payment won't land in your bank account exactly as calculated — Uncle Sam always wants his share. Knowing your after-tax income will help you budget without any unpleasant surprises.
You've Got This!
See? Calculating your pension isn't the dark art everyone makes it out to be. It's just three simple numbers multiplied together, a few adjustments, and a little bit of common sense sprinkled on top. You've already conquered harder things in life — this is basically a victory lap.
So go ahead, grab that calculator, punch in your numbers, and let yourself get excited about what's coming. Retirement is supposed to be the fun part — the part where you finally get to enjoy the fruits of all your hard work. And honestly? You've earned every single penny. Cheers to your future — it looks amazing from here! 🎉
