How To Manage Assets And Liabilities

" Alright, friend, let's talk about something that sounds boring but is actually 🔥 important: managing your assets and liabilities. Don't worry, I'm not going to put you to s...

Alright, friend, let's talk about something that sounds boring but is actually 🔥 important: managing your assets and liabilities. Don't worry, I'm not going to put you to sleep with accounting jargon. We're keeping this light, fun, and totally doable!
Okay, But What Even Are Assets and Liabilities?
Think of assets = things that put money in your pocket. Think of liabilities = things that sneak money out of your pocket. Simple, right?
Your savings account, your house, your Pikachu-themed comic book collection (hey, if it's worth money, it counts) — all assets! Your car loan, your credit card debt, that crispy little student loan — those are liabilities. Bummer, I know.
Must Read
The Golden Rule: Make Your Assets Outweigh Your Liabilities
This is essentially what being "wealthy" means in the real world. When your assets minus liabilities gives you a positive number, high five yourself! 🙌
If it's negative, don't panic. Most people start there, and they still turn it around. We're all works in progress, right?
Step 1: Get Fancy (Just Kidding) — Make a List
Grab a notebook, open your notes app, or grab a napkin — it doesn't matter. Write down every single asset you own and its approximate value.
Now do the same for every liability: loans, debts, outstanding bills. Don't feel bad about it; knowing exactly where you stand is surprisingly freeing.
You'd be shocked how many people genuinely have no idea how much they owe. Spoiler: it's a lot of people.
Do the Big Subtraction
Take your total assets, subtract your total liabilities, and boom — that's your net worth. No, not the same as salary. Salary is your income; net worth is literally your financial snapshot.
If your number is positive, congratulations are in order! If it's negative, congratulations anyway — because now you know your starting line.
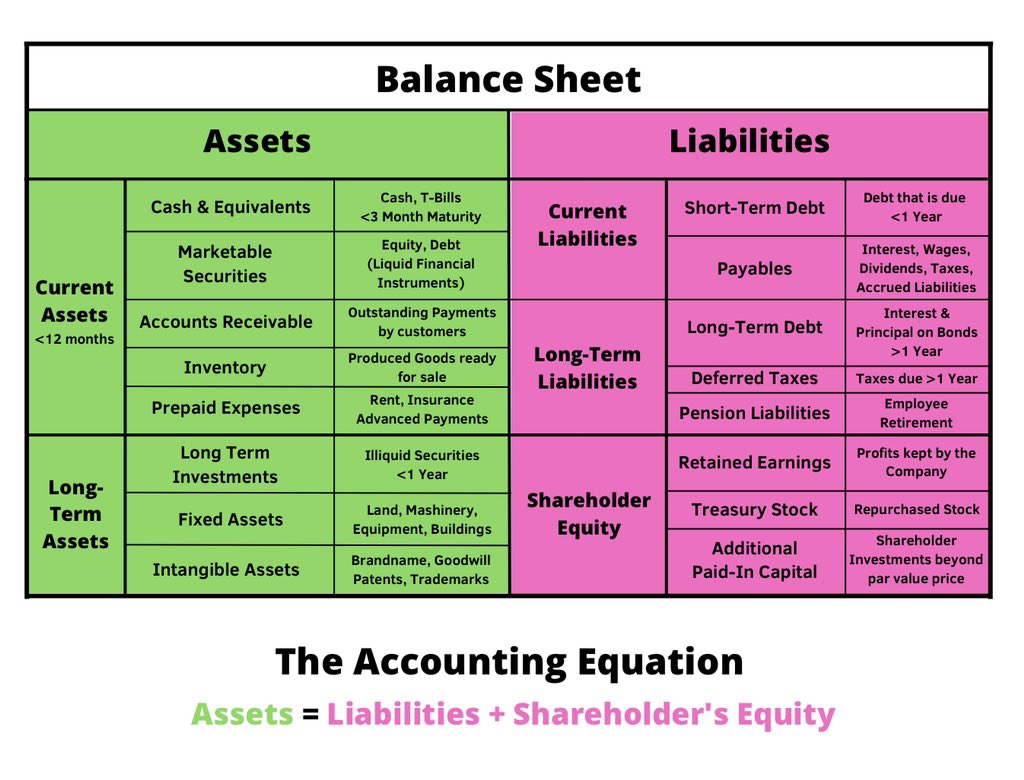 Chart Of Accounts Assets And Liabilities
Step 2: Shrink Those Liabilities Like a Left-Behind T-Shirt
Here's the fun part: tackling your debt with some serious determination. Tackling debt with a plan is like closet-decluttering — surprisingly satisfying, and yes, a little painful at first.
Prioritize Like a Boss
List your debts from smallest to largest, or attack the one with the highest interest rate first. Both strategies work — pick whichever keeps you motivated.
The Avalanche Method targets high interest. The Snowball Method targets small balances. Funny enough, both make you feel like a debt-slaying wizard. 🧙
Stop Adding to the Pile
If you keep borrowing while trying to pay off debt, it's like bailing water out of a boat with no drain plug. Freeze the credit card spending while you're in repayment mode.
Cut unnecessary subscriptions, eat out less, and maybe ghost that expensive gym membership you never use. Brutal? A little. Necessary? Absolutely.
Step 3: Grow Those Assets Like a Houseplant That Survives You
Now let's flip to the exciting side: building up your assets. The goal is to make them multiply, not just sit there looking cute.
Automate Your Savings
Set up automatic transfers to your savings or investment accounts every payday. You'll barely miss the money, and suddenly you're accumulating wealth like a sneaky pro.
 Asset-Liability Management Matrix [Free download]
Even starting small — like even $50 a month — accelerates over time thanks to compound interest. Einstein reportedly called it the most powerful force in the universe, which is way cooler than boring old gravity.
Diversify or... Well, Don't
Don't put all your eggs in one basket unless you plan on making one enormous omelet. Spread your investments across stocks, bonds, real estate, or index funds.
Diversification means if one area dips, another might rise. It's like having emotional backup plans for your money — smart and slightly dramatic.
Invest in Yourself
Here's a sneaky asset people forget: you. New skills, certifications, side hustles — these directly boost your earning power.
The higher your income potential, the easier it becomes to buy assets and eliminate liabilities. It's a beautiful virtuous cycle!
Step 4: Review, Adjust, Repeat
Life changes, and so should your financial strategy. Do a quick check-in every quarter — that's every three months for those who skipped that class.
Reassess your liabilities: any paid off? Any new ones crept in? Look at your assets: are they growing, shrinking, or doing a weird little wiggle?
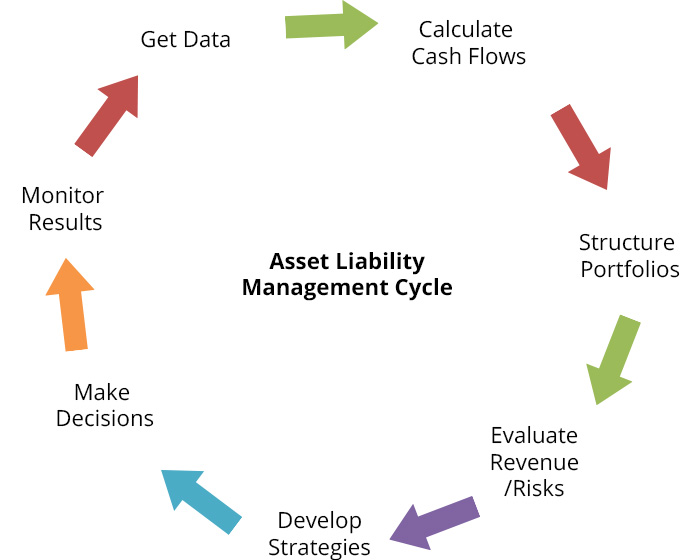 Asset Liability Management | EuroRisk Systems Ltd.
Small tweaks consistently lead to dramatic improvements over a year. It's honestly less painful than a huge, chaotic overhaul later.
Keep the Fun Visual Trick Going
Imagine your financial life as a seesaw. On one end: assets. On the other: liabilities. Your job is to lift the asset end while pressing down the liability end.
See yourself beating liabilities and growing assets with every small win. Track progress somewhere visible — a whiteboard, a chart, even sticky notes on the fridge.
Okay, You're Ready!
Managing assets and liabilities isn't some secret club for finance bros. It's just understanding what you own and what you owe, then making tiny moves every week.
The fact that you've read this far means you're already ahead of most people. Your future self is doing a happy little dance as we speak.
Keep going, stay curious, and remember: every legitimate progress counts. You've got this, friend — and honestly? Your bank account is about to thank you for it. 💛
"