Present Value Vs Net Present Value

Let's be honest—finance terminology can feel like a foreign language sometimes. But two concepts that pop up everywhere are Present Value (PV) and Net Present Value (NPV). Don...
Let's be honest—finance terminology can feel like a foreign language sometimes. But two concepts that pop up everywhere are Present Value (PV) and Net Present Value (NPV). Don't worry; by the end of this article, you'll feel like you've got them down.
Think of them like two cousins at a family reunion. They look similar, wear almost the same outfit, but have slightly different personalities once you get to know them.
What Is Present Value Anyway?
Present Value is all about understanding what a future amount of money is worth right now. Imagine your grandmother promises you $100 in a year—would that $100 come as a surprise if you received it today instead?
Must Read
Of course it wouldn't. But the reality is, money changes value over time because of things like inflation, interest rates, and the simple idea that a dollar today can earn you more if you invest it.
Let's say you could earn 5% interest in a savings account. If someone offered you $100 one year from now, you'd only need about $95.24 today to grow it into $100 by then.
So your friend's future $100 has a present value of roughly $95.24. That little difference is basically the cost of waiting—and the power of growing money over time.
A Quick Everyday Example
Imagine two friends, Sam and Alex, each hand you a $500 gift card—one for today, the other for three years from now. Which one would you open first? Almost everyone snatches the immediate gift card without thinking twice.
That instinct is your brain doing present value math on autopilot. You intuitively know that $500 today is better than $500 later because you can use it right away or put it to work.
 Present Value vs Net Present Value | Top 7 Differences (With Infographics)
Now, What About Net Present Value?
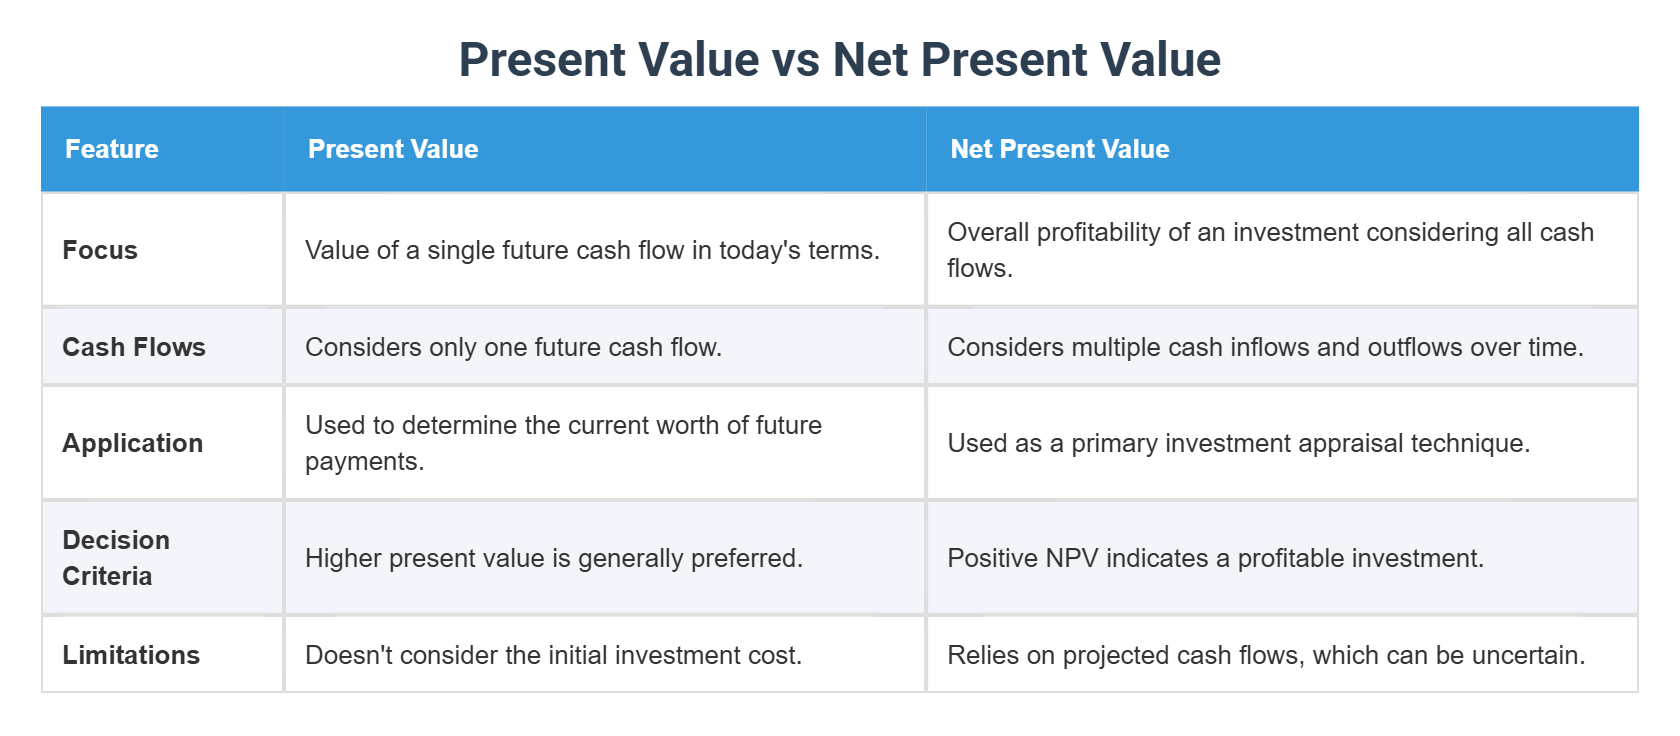
Net Present Value takes things one step further. While PV tells you what future money is worth today, NPV tells you whether an entire project or investment is actually worth it after subtracting the initial cost.
It's as if you finally opened both gift cards, used them, and then calculated whether the whole experience left you better off than if you'd done nothing.
The formula sounds fancy, but the idea is simple: NPV = Present Value of Inflows - Present Value of Outflows. If the result is positive, you're winning. If it's negative, you might want to rethink the deal.
The Lemonade Stand Story
Picture this: Your neighbor's kid wants to open a lemonade stand. She needs $50 for supplies (lepmons, cups, sugar, etc.), and she expects to earn $60 over the summer.
If we ignore time for a moment, she'd make a sweet $10 profit. But what if we factor in that the $60 trickles in over three months and she could have earned a little interest elsewhere?
After calculating the present value of those future earnings and subtracting her $50 cost, her NPV might come out to something like $7 instead of $10. Still positive, so the stand is still a go—but now she knows the real picture.
 Graphic of Net Present Value and Present Value Vs. Discount rate
PV vs. NPV: What's the Difference Really?
The simplest way to remember it is this: Present Value is about evaluating one single sum of money, while Net Present Value compares the total inflows against total outflows of a whole project.
PV helps you understand the worth of a specific future payment. NPV helps you decide whether an entire business idea, investment, or purchase makes financial sense.
Analysts, accountants, and entrepreneurs all rely on NPV every day because it gives them a clear yes-or-no signal. A positive NPV means go for it; a negative NPV means walk away.
Why Should You Care?
You might not be running a company or managing a portfolio of stocks, but these ideas sneak into everyday decisions more often than you'd think.
Consider buying a car with monthly payments versus paying cash upfront. Or choosing between receiving a bonus now versus waiting for a raise next year. These are quietly present value questions in disguise.
 Graphic of Net Present Value and Present Value Vs. Discount rate
Understanding PV helps you make smarter personal choices, and understanding NPV helps you evaluate bigger commitments like starting a small business or renovating your home.
Think of It as Financial Empathy
When you grasp these concepts, you stop just looking at the sticker price and start seeing the full story behind the numbers. It's like finally understanding why the movie critic didn't like that film you loved—there's more context than the surface glance.
You begin asking better questions: Is this deal actually profitable over time? Am I undervaluing money I'll receive next year? These are powerful, money-saving thoughts.
Wrapping It Up
Present Value tells you what future money is worth today, and Net Present Value tells you whether a whole project's gains outweigh its costs in today's dollars. Together, they form a dynamic duo that keeps financial decisions grounded in reality.
Next time someone casually mentions NPV at a dinner party, you won't need to fake a nod. You'll actually know what they're talking about—and that's a pretty satisfying feeling.
So here's your takeaway: PV looks at the value of money over time, and NPV looks at the bottom line of a whole decision. Master these two, and you'll feel a lot more confident with every financial choice life throws your way.
