Does A Severance Package Get Taxed

So, you just got handed a severance package. First of all, congrats — not because getting laid off is fun (it totally isn't), but because at least someone is paying you to lea...
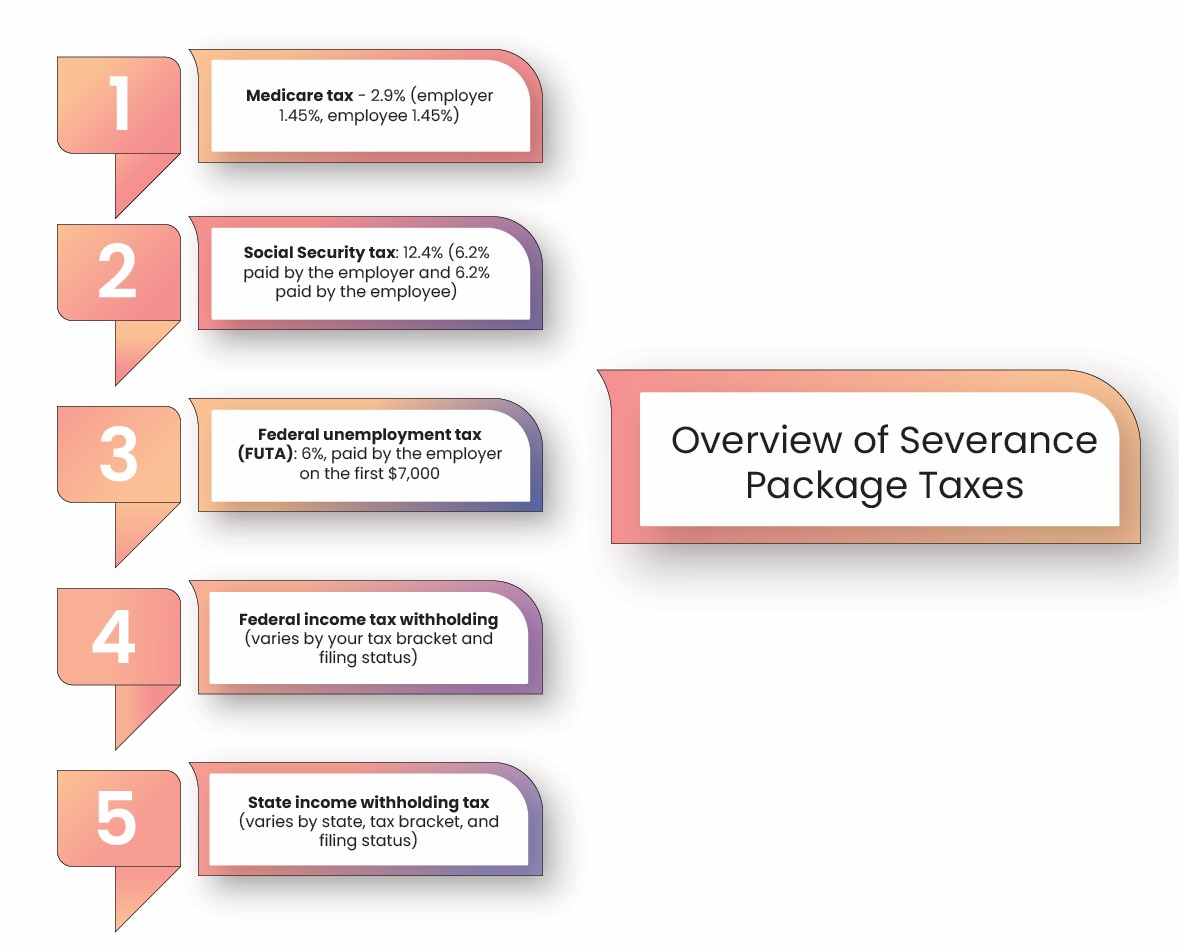
So, you just got handed a severance package. First of all, congrats — not because getting laid off is fun (it totally isn't), but because at least someone is paying you to leave. Now let's talk about the real question eating at your brain: does a severance package get taxed?
The short answer? Yes. Sorry, pal. The long answer is a little more interesting, and honestly, it's worth understanding before you start dreaming about that new camera or road trip.
What Exactly Counts as a Severance Package?
Okay, so not all severance looks the same. Some companies give you a lump sum. Others spread it out over weeks or months. And some throw in perks like COBRA coverage or unused vacation pay — oh, the luxury.
Must Read
All of that money — the cash, the vacation payout, even the bonus checks — falls under the umbrella of severance. And guess what? The IRS considers all of that taxable income. No exceptions, no loopholes, no "but I didn't ask for it" excuses.
It's Treated Like Regular Wages
Here's the thing most people don't realize. Severance pay gets taxed the same way your regular paycheck does. That means federal income tax, state income tax, Social Security, and Medicare all take their cut. It's basically like you're still working — except now you're not.
Yep, that feels unfair. Welcome to life, friend.
But Won't My Employer Handle the Taxes?
Most employers will withhold taxes from your severance just like they would from a normal paycheck. So technically, you won't owe a surprise tax bill at year-end — if they do it right.
 Severance Package Taxable PowerPoint Presentation and Slides PPT
But some companies mess it up. Or worse, they give you the whole check upfront and say, "Good luck!" Then guess who's staring down a tax bill in April? You.
The Supplemental Wage Thing
Here's a fun little detail: severance could be classified as a supplemental wage. If that's the case, your employer might withhold a flat 22% federal tax rate. Sounds high? Wait — if your regular tax bracket is higher than 22%, you could owe even more when you file.
Fun, right? (No. No it's not.)
Can I Lower My Tax on Severance?
Actually, yes — and this is the part where we high-five over coffee. You've got a couple of strategies to soften the blow.
Contribute to a Tax-Advantaged Account
If you put part of your severance into something like a 401(k) or an IRA, you can reduce your taxable income for the year. Just make sure your severance plan actually allows contributions. It's worth a phone call.
 What You Need to Know About Severance Packages & Taxes | Optima Tax Relief
Even a small dent in your taxable income saves real money. We're talking hundreds or even thousands — not chump change.
Timing Is Everything
Your severance hits based on when you received it. If it lands in a year where your income is still relatively low (because you were only working part of the year), you might dodge your highest tax bracket. Imagine that.
Conversely, if it all piles up in December? Ouch. Plan ahead, people.
What About the Benefits and Perks?
Not everything in your severance package gets taxed the same way. If your company covers health insurance premiums during the severance period, those could be tax-free up to certain limits. Nice.
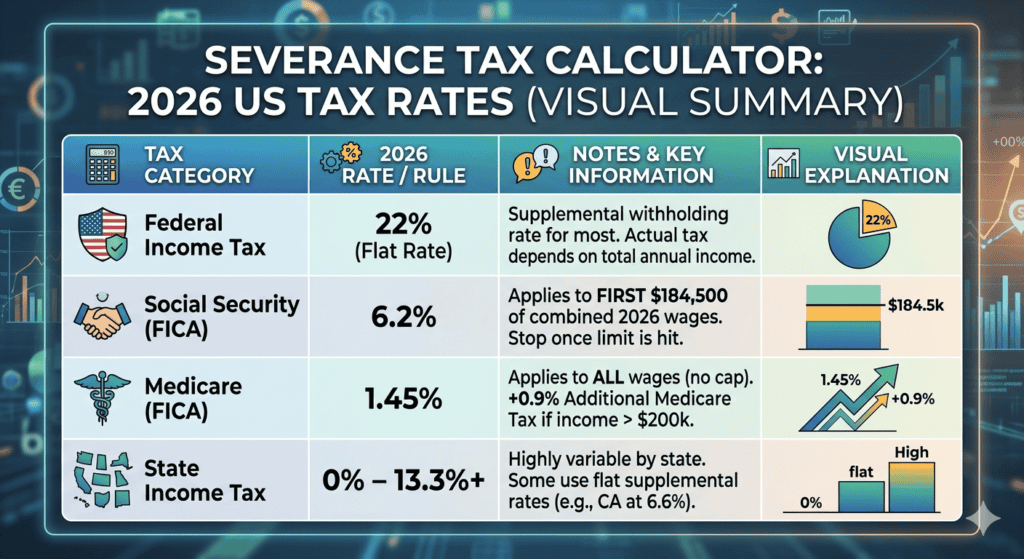 Severance Tax Calculator: Estimate Net Severance After Withholding (US
Lump sum payments, unused PTO, and cash — those are all in for the full tax treatment. The IRS has a very long memory and a very sharp pencil.
Stock Options? Uh-Oh...
If your severance includes stock options or equity, you might face capital gains tax on top of everything else. This can get complicated fast, so honestly? Talk to a tax professional. Don't wing it.
The Bottom Line
Here's your coffee-table summary: yes, severance gets taxed, and no, it won't magically avoid the IRS. But with a little smart planning — contributions, timing, and maybe a pro in your corner — you can keep more of that money in your pocket.
The recovery fund you planned? Still doable. The big "treat yourself" moment? Maybe just not as extravagant as you imagined. Either way, you're navigating this now, and that puts you ahead of most people.
Now sip your coffee and plan your next move. You've got this.
