Does Net Worth Include Home Equity

Alright, pull up a chair. I've got coffee (or wine, no judgment) and we need to talk about something that bugs people way more than it should. Does your net worth include home...
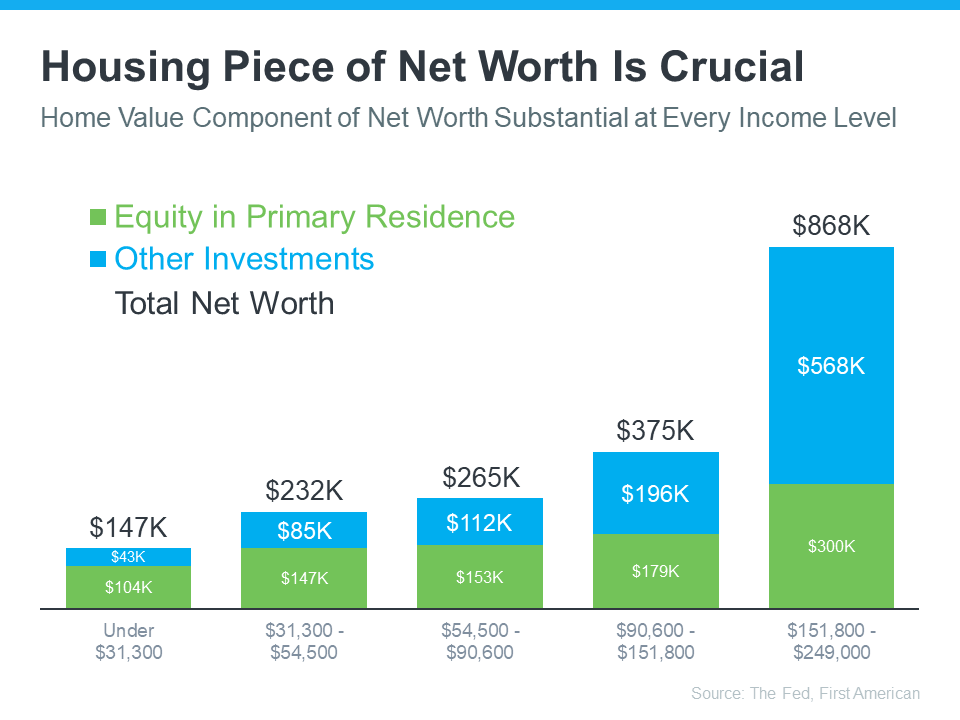
Alright, pull up a chair. I've got coffee (or wine, no judgment) and we need to talk about something that bugs people way more than it should. Does your net worth include home equity? Spoiler alert—it's a little more complicated than a simple yes or no.
The Quick Answer First
Okay, so the short version? Yes, home equity absolutely factors into your net worth. Now go pour yourself another cup because the long version is where things get spicy.
But Wait, What Is Net Worth Really?
Think of net worth as your financial report card. It's just a fancy way of saying: everything you own minus everything you owe. That's it. Literally that simple.
Must Read
So you take all your assets—cash, investments, cars, that vintage baseball card collection (yes, we're counting it)—and subtract all your debts. Mortgage, student loans, credit card debt, the IOUs you owe your sister.
The number you're left with? That's your net worth. No drama, no secrets.
Home Equity: The Star of the Show
Now let's zoom in on the star of today's chat. Home equity is the portion of your home that you actually own outright. It's your home's market value minus what you still owe on the mortgage.
Let's say your house is worth $400,000. You still owe $250,000 on the mortgage, so your home equity is $150,000. Not bad at all, right?
This is a real asset. It's concrete, measurable, and it sits right there as part of your financial picture. So yeah, most financial gurus absolutely include it in net worth calculations.
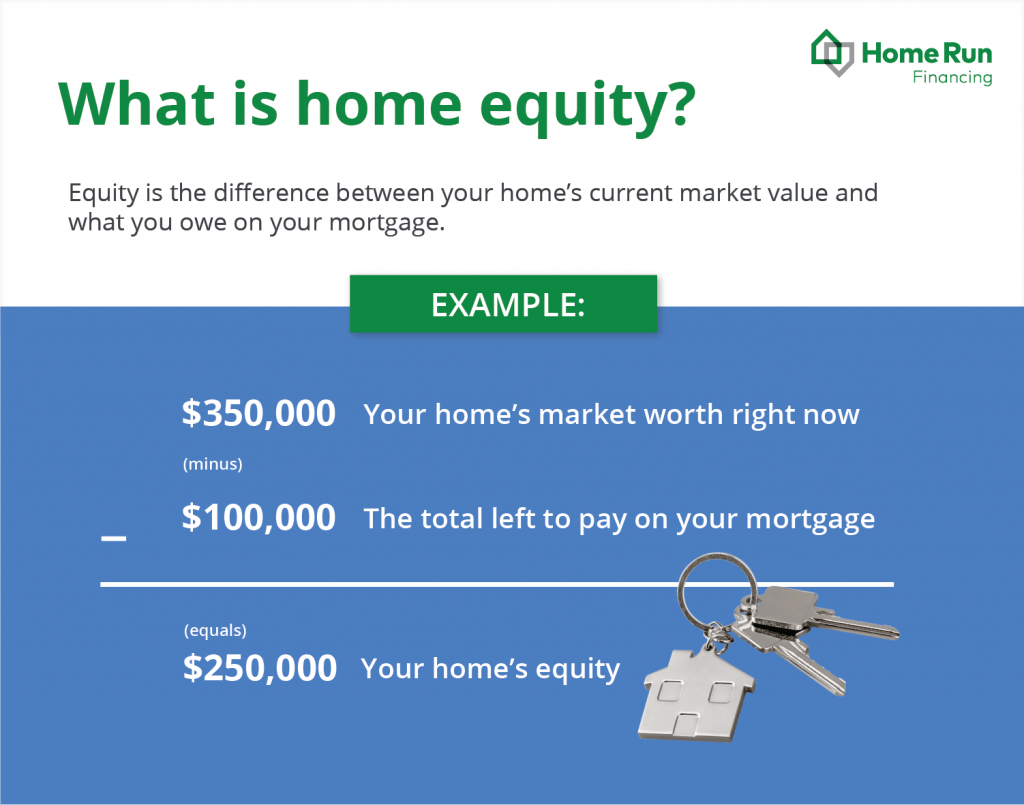 Home Equity Net Worth – Home Equity and Net Worth: What’s The
Why Some People Leave It Out
Hold on though. Some folks deliberately keep home equity out of the equation. Why? Because your house doesn't exactly pay the bills—unless you sell it, of course.
Sharing a home is more like locked-up wealth. You can't spend it at the grocery store. So some people prefer to track what they call "investable net worth" instead.
It's sort of like having a million dollars buried in your backyard. Cool, technically you're wealthy, but you're not buying dinner with dirt, you know?
The Two Types of Net Worth
This is where I like to tell people there are really two flavors of net worth. You've got total net worth and liquid or investable net worth.
Total net worth includes everything—the house, the equity, the car, the kitchen sink if you could sell it. Investable net worth skips the house and focuses on what you could actually access without major life decisions.
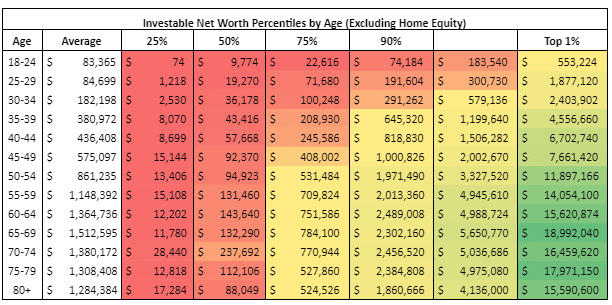 Net Worth by Age: How Do You Compare to Your Peer Group? - Wealthtender
Neither one is wrong. They're just measuring different things. Think of them like two lenses on the same camera.
What Should You Actually Do?
Here's my honest, friend-to-friend advice. Track both. Keep your total net worth number because it's motivating to see it grow over time.
But also keep an eye on your investable net worth. That's the number that tells you how much financial flexibility you really have when life throws curveballs.
Because let's be real—knowing your house is worth $500,000 feels great. But knowing you've got $75,000 in savings and investments feels even better when an emergency hits at 2 AM.
Mortgage Paydown Speeds Things Up
Here's a fun fact. Every month you make a mortgage payment, your home equity goes up. It's like a slow-motion wealth-building machine running quietly in the background.
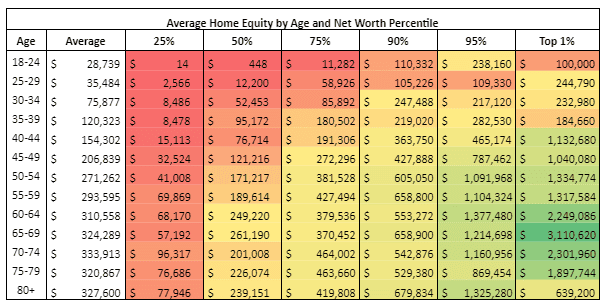 Net Worth by Age: How Do You Compare to Your Peer Group? - Wealthtender
Over the years, this adds up big time. Some homeowners have hundreds of thousands in equity and don't even realize how wealthy they've quietly become.
So if that mortgage feels painful now, remember—it's actually boosting your net worth with every single payment. Silver lining, right?
And There You Have It
So does net worth include home equity? Absolutely, yes. Unless you specifically decide to track it separately for personal reasons—and that's totally fine too.
The most important thing is that you know your number. Whether it's $50,000 or $5,000,000, awareness always beats guessing.
Now finish your coffee. You've earned a peek at your finances today. Your future self will thank you for asking this question. 😊
