Is 2.2 Million Enough To Retire

So, you've done the math. You've stared at your retirement account until your eyes went cross-eyed, and you've landed on the magical number: 2.2 million dollars. Now the only...

So, you've done the math. You've stared at your retirement account until your eyes went cross-eyed, and you've landed on the magical number: 2.2 million dollars. Now the only question is — can you actually retire on that, or will you be forced to sell handmade dream catchers at a farmers' market for the rest of your life?
Let's find out, because nobody wants to end up in their seventies eating canned beans three times a day. Elastic waistbands are comfortable, sure, but they're not a retirement plan.
The Golden Rule: The 4% Withdrawal Strategy
Most financial planners swear by the 4% rule, which means you should only withdraw about 4% of your portfolio each year. On 2.2 million, that comes out to roughly 88,000 dollars per year before taxes. That's not yacht money, but it's definitely "order the guac without thinking" money.
Must Read
Now, before you start picking out your cocktail umbrellas, let's talk about inflation. The dollar loses about 3% of its purchasing power every single year, which means your 88 grand in twenty years will feel more like 48 grand. Money doesn't just get old — it gets lazy.
Where You Live Matters (A Lot)
Here's where things get wild: living in San Francisco on 2.2 million is a whole different game than living in Tulsa, Oklahoma. Your rent alone in the Bay Area could eat through your retirement faster than a Golden Retriever eats dropped snacks. Location is honestly the biggest secret weapon in retirement planning.
On the flip side, if you're in a low-cost area of Texas or the Midwest, 88K a year puts you in a pretty comfy place. You could have a mortgage-free home, a decent car, and still afford to yell at your smart TV when it can't find Netflix. Living well on less is totally possible — just don't expect Hollywood glamour.
 Is $2 Million Enough to Retire: Unlock Worry-Free Retirement
Health Care: The Sneaky Budget Killer
If you retire before Medicare kicks in at 65, health insurance becomes like that coworker who never brings a snack to the party — frustrating and expensive. A couple could easily spend 12,000 to 20,000 dollars a year on premiums. And then there are deductibles, copays, and that mysterious charge called "facility fee" that seems to exist purely to ruin someone's day.
A single major health event can throw your carefully crafted budget right out the window. One surprise surgery and suddenly you're Googling "Can I still work at 67?" for the third time this month. Health care isn't just important — it's the silent assassin of retirement dreams.
Taxes: Because Nothing Is Truly Free
All that 401(k) money you saved so diligently? The IRS would like a word. withdrawals from traditional retirement accounts are taxed as regular income, which means a chunk of that 88,000 disappears before it even hits your bank account. Uncle Sam's always at the table, and he never brings a dish to pass.
 I'm 62 With $2.2M. How Much Can I Spend In Retirement? - YouTube
Strategic withdrawals from Roth accounts or tax-efficient investment accounts can help you keep more of what's yours. But without some tax planning, you might end up paying more to the government than to your dentist. Smart tax strategy is like a secret password — unlock it, and the game gets way easier.
What About Social Security?
Many retirees also collect Social Security, which currently averages around 1,800 dollars per month. If you delay claiming until 70, that monthly check gets noticeably fatter. So imagine that's an extra 20,000+ dollars a year stacking on top of your 88K — that's suddenly looking pretty comfy.
Of course, Social Security might not be available in its current form forever, so treat it as gravy rather than the main course. It's the bonus round on the game show of adulting. Never count on it entirely, but definitely enjoy it if it's there.
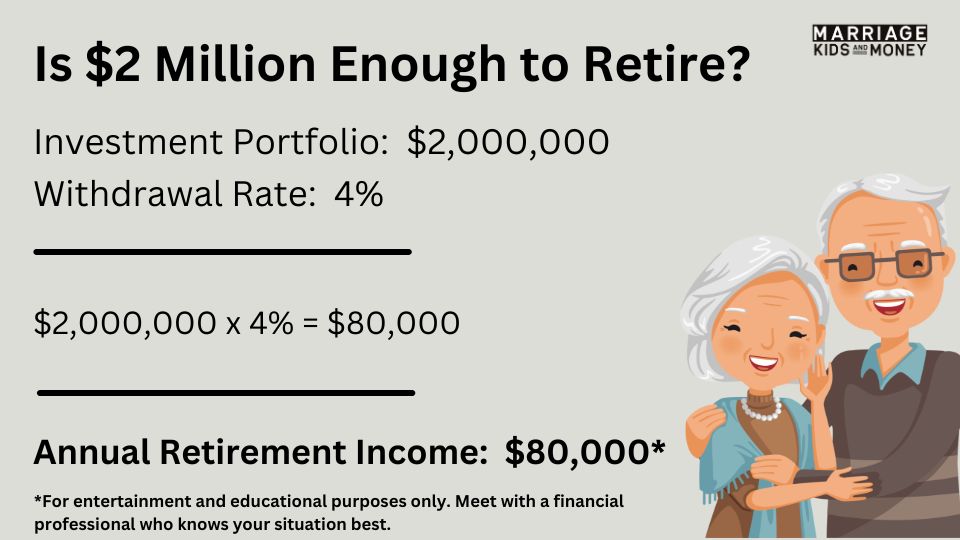 Am I On Track for Retirement? – Marriage Kids and Money
The Verdict: Is 2.2 Million Enough?
The honest answer? For many people, yes — with some caveats. If you're disciplined with spending, live in a reasonable cost-of-living area, and stay on top of health care costs, 2.2 million can absolutely support a comfortable retirement. Throw in Social Security and smart investing, and you're in solid shape.
But if you've got a mortgage in Manhattan, a taste for five-star dining, and a yacht habit, you're going to need to either downsize dramatically or win the lottery. The key is flexibility — the ability to adjust your lifestyle as your portfolio grows or dips.
So grab your coffee, relax, and remember: 2.2 million might not buy you paradise on a tropical island. But it can absolutely buy you a peaceful morning at a café, writing your own rules. And honestly? That beats selling dream catchers any day.
