What Is A Vested Balance 401k

Okay so, let's talk about something that confuses the absolute heck out of everyone: vested balances in your 401(k). You're working hard, contributing money, watching that acc...

Okay so, let's talk about something that confuses the absolute heck out of everyone: vested balances in your 401(k). You're working hard, contributing money, watching that account grow, and then one day you wonder, "Wait… do I even own all of this yet?" Fair question. Especially when you're thinking about switching jobs (or daydreaming about it, no judgment).
The truth is, retirement savings can feel like a mystery wrapped in paperwork. But trust me, once we break this down, it'll all make sense. So grab your coffee and let's dive in — no financial degree required here.
The Basics: What Even Is a Vested Balance?
A vested balance is simply the portion of your 401(k) account that's yours to keep. Yep, just like that jacket you finally paid off — it's yours, baby. Anything that's not vested? Well... that's a different story.
Must Read
Most 401(k) plans have two main funding sources. You've got your own contributions, which are always 100% yours right away — even if you quit tomorrow, they're coming with you (or at least the cash equivalent). Then there are employer matching contributions, and those usually follow their own vesting schedule.
So your vested balance is basically the money in the account that no one can take back once you walk out the door. Think of it as your financial "insurance policy" against a messy exit. Anything unvested? Consider it the part that disappears when you say "I quit."
How Does Vesting Actually Work?
Employers typically use one of a few common methods to figure out your vesting progress. The most popular ones are graded (or cliff) vesting and immediate vesting. And yes, they sound like financial flavor names from a coffee shop menu.
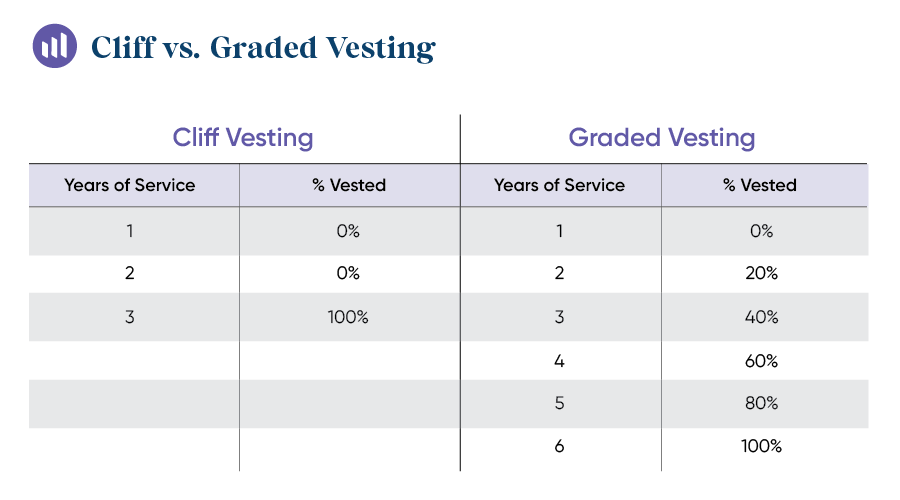
Cliff vesting is the "all or nothing" approach — you don't vest anything until a certain milestone, commonly three to five years. Then boom, you're fully vested overnight. It's dramatic, kind of like a season finale.
 401(k) Vesting 101 – Slavic 401k – What Is 401(k) Vesting
Graded vesting is more gradual. You earn ownership of those employer contributions a little bit each year. So after year one, maybe you're 20% vested, and it climbs from there. Smooth and steady.
Does My Own Contribution Get Affected?
Great news — your own money doesn't get affected by vesting. That's already 100% yours no matter what. Only the employer's matching dollars are on the chopping block here.
This is actually why personal contributions are a big deal. Even if your employer contributions vanish upon departure, your own contributions stay intact. So you're never starting from absolute zero.
Why Should You Care About Your Vested Balance?
Because every dollar in your vested balance is a dollar you can roll over, transfer, or cash out without losing anything. That's huge. Especially when you're making big decisions like changing jobs or planning your exit strategy.
 What Is Vesting? 401(k), Stock Grants, and Pensions Explained
Let's say your 401(k) holds $50,000 total, but only $30,000 is vested. If you leave today, the missing $20,000 stays with your employer. Poof. Gone like it never existed in your world. Brutal, right?
On the flip side, knowing your vesting schedule lets you make smarter career moves. Run the numbers before jumping ship — maybe that extra year of vesting is worth sticking around. Or maybe it's not. Your call.
Employer Bankruptcy? Wait...
Here's a bonus fact that people don't usually know: if your employer goes bankrupt or goes out of business, ALL your 401(k) contributions are immediately fully vested. Every single dollar, including their matching portion. That plan has to be maintained or transferred for participants.
So no, you can't lose employer contributions because a company implodes. At least not if they funded them correctly. The government does eventually step in to protect you — small mercies.
 Your 401K: 11 Important Questions Answered
How Do You Check Your Vested Balance?
Most 401(k) plans give you online access to your account, and your vesting status is usually front and center. It'll tell you exactly what's yours and what's still in limbo. Check it regularly — awareness is everything.
You can also call your plan administrator or HR and ask straight up. They deal with these questions all the time, so don't feel weird about asking. It's your money — you deserve full transparency.
Pro tip: keep a mental note of your vesting schedule every time it changes. Future you will absolutely thank present you for this. Especially if you ever find yourself in a "should I leave?" crisis with coffee in hand.
The Takeaway
Your vested balance is the part of your 401(k) that you truly own — no strings attached. It matters because it directly impacts what you get to keep when you leave a job. Always keep an eye on it.
Understanding vesting isn't glamorous, but it's incredibly practical. Think of it as financial self-defense. And hey, now you're basically a 401(k) expert — time to wow your friends at the next birthday party. You've earned those bragging rights.
