How To Calculate Net Income Using Assets And Liabilities

Picture this: It's a Sunday morning, you're scrolling through your phone with a cup of coffee in hand, and a random question pops into your head — what am I actually worth? No...

Picture this: It's a Sunday morning, you're scrolling through your phone with a cup of coffee in hand, and a random question pops into your head — what am I actually worth? Not in a philosophical way, but in a cold, hard numbers kind of way. Welcome to the surprisingly fun world of calculating net income through your assets and liabilities.
The good news? You don't need an MBA from Harvard to figure this out. The math is simpler than choosing what to order at brunch.
What Are Assets, Anyway?
The Stuff You Own
Assets are essentially everything you own that holds monetary value. Think of your savings account, your car, the laptop you're reading this on, or even that vintage vinyl collection gathering dust on your shelf.
Must Read
So if you've ever wondered whether your sneaker collection qualifies — yes, it can, especially if those Jordans keep appreciating like fine wine. The IRS even lets you claim certain collectibles as taxable assets in specific cases.
Make a quick list of everything worth money. Be honest — missed items often reveal more value than you'd expect.
Categories That Matter
Assets typically fall into liquid and non-liquid categories. Cash, stocks, and bonds are liquid because you can convert them to money quickly, while real estate and jewelry take longer to sell.
Understanding where each asset sits on this spectrum helps you plan smarter financial moves later on. A quick pro tip: always separate the two when balancing your numbers.
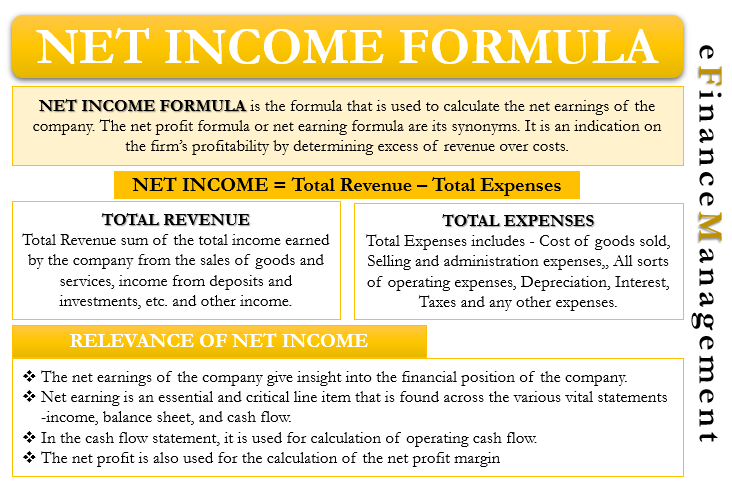 Accounting Net Income
What About Liabilities?
The Weight You Carry
Liabilities are simply everything you owe. Your mortgage, car payments, credit card balances, student loans — the list can feel long, but naming them is the first step to shrinking them.
Think of liabilities as the financial equivalent of carrying too many bags at once. Set them down, count them properly, and the load suddenly feels manageable.
Funny enough, the average U.S. household carries over $100,000 in total debt, which means you're far from alone in this exercise.
Short-Term vs. Long-Term
Just like assets, liabilities come in two flavors: short-term and long-term. Credit card balances are short-term, while your thirty-year mortgage stretches into long-term territory.
Grouping them this way gives you a clearer snapshot of your immediate obligations versus distant ones. It also makes budgeting feel less like guesswork and more like strategy.
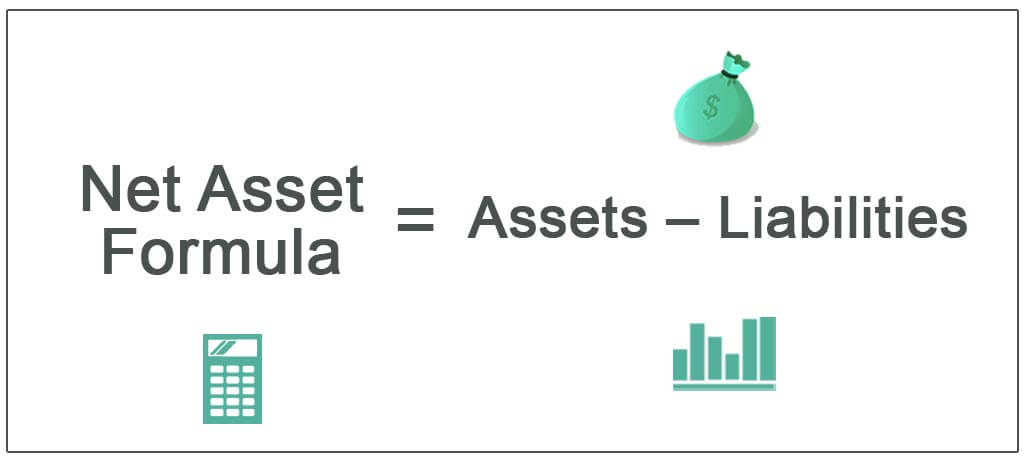 Total Net Assets Formula | Total Liabilities / Total Assets: What Is It
The Core Formula
Assets Minus Liabilities
Here's where the magic happens: take your total assets, subtract your total liabilities, and the result is your net income — or more precisely, your net worth in this asset-based context.
For example, if you own $250,000 in assets and owe $150,000 across debts, your net position sits at a comfortable $100,000. That single number tells a powerful story about where you stand financially.
Feeling a shiver of satisfaction? That's the numeric equivalent of finally knowing your score in a game you've been playing blindfolded.
Do It Step by Step
First, gather bank statements, property estimates, and loan documents in one place. Second, sum every asset, then sum every liability — no rounding, no estimating, just clean numbers.
Third, subtract and write the result where you can see it daily. Albert Einstein reportedly said compound interest is the eighth wonder of the world, but honestly, clarity feels like a wonder too.
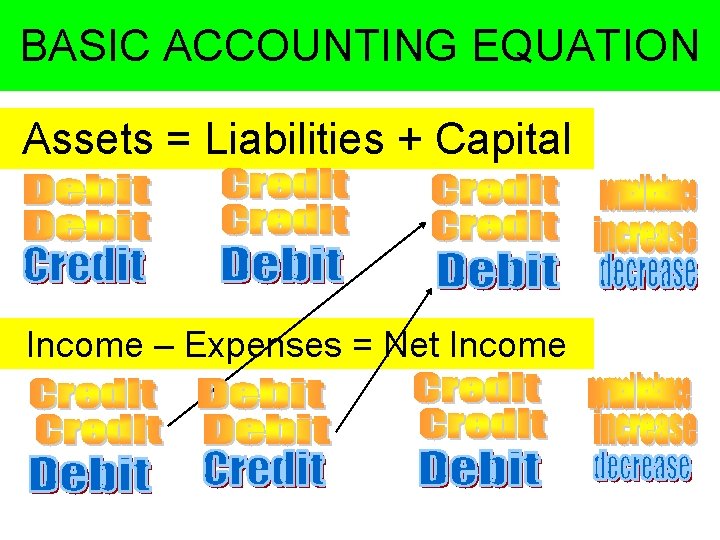 Review of the Previous Lesson Week 2 ACCOUNTING
Practical Tips to Keep You Sharp
Use a spreadsheet or a simple app like Mint or YNAB to track everything in real time. A study from the National Endowment for Financial Education found that people who track finances monthly improve their scores within six months.
Refresh your asset valuations quarterly — your car depreciates while your retirement account may quietly be growing three times faster. Small updates prevent big surprises down the road.
And here's a cultural nugget: the Romans used a concept called "patrimony" — essentially personal net worth — to determine social standing centuries ago. So yes, counting wealth has been cool since BC.
The Reflection
At its heart, calculating net income through assets and liabilities isn't about chasing perfection; it's about awareness. Every number you crunch brings you one step closer to a life built on intention rather than instinct.
In daily life, this habit mirrors something bigger — knowing what you carry and what you shed so you can move forward lighter and wiser. Grab your ledger, take a breath, and let those honest numbers guide your next chapter.
